



Trading Places
Ally Financial and GM Financial are both entering new phases in their evolution, and the moves they’re making were on display at NADA 2015.

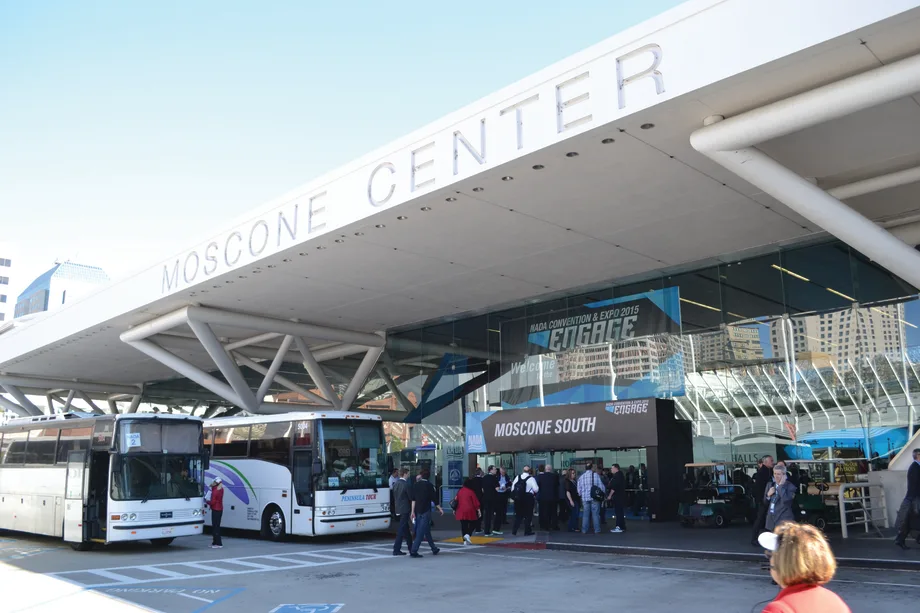
It was a tale of two conventions for Ally and GM Financial at the National Automobile Dealers Association’s annual get-together in January. While Ally cut what may be the last remaining link to its General Motor Acceptance Corp. roots, GM Financial touted its latest moves to fill the role Ally once held as GM’s captive finance arm.
Inside the south hall of San Francisco’s Moscone Center, Ally executives previewed a new vehicle service contract (VSC) called Ally Premiere Protection (APP), as well as a new administration platform that will allow dealers to electronically contract, rate and remit the new offering.
Doug Timmerman, president of Ally Insurance, described the new VSC as an enhanced version of the company’s General Motors Protection Plan (GMPP), a brand name the former captive will lose rights to in November 2016. He said Ally is getting ahead of that deadline to make clear its products and services are available to dealers representing all brands.
The biggest difference with APP is coverage. Whereas GMPP offered up to 10 years or 100,000 miles of coverage, APP can go up to 12 years and 150,000 miles. It also offers more options and pricing based on time in service, mileage, make and model for all vehicle brands.
Ally Insurance will begin piloting the new VSC and administration platform this month, with nationwide rollout expected to begin this summer. “The launch of Ally Premiere represents an important development in the evolution of Ally’s dealer products and services, and better positions us to respond to the needs of a diverse dealer network,” Timmerman said.
Inside Moscone North, GM Financial’s Kyle Birch touted the subprime lender-turned-captive’s busy 2014, a year in which it rolled out its first prime APR product in November and its first floorplan financing product in May. “The biggest thing for us in 2014 is we spent a lot of time and investment on bringing all our systems together, understanding that we were going to get in the prime business from an APR perspective,” he said.
The company also began working on applications that will drive a better connection between customers, GM and its dealer network — an initiative being led by Will Stacy, senior vice president of digital and technology services. “We’re trying to build integration tools with GM so you can apply for credit in an easier way through its sites and through its dealers’ sites,” Stacy said. “So the idea is we’d offer an application or widget that goes on dealership sites so you can apply for a GM Financial loan through one of those 4,200 dealer websites that GM and Cobalt host, as well as a beefed-up customer experience with native application on iPhones, Androids and customer portals.”
The big announcement was GM’s decision to end its leasing relationship with Ally Financial and U.S. Bank, with GM Financial, which launched its first leasing product 90 days after it was purchased by GM in 2010, officially becoming the OEM’s exclusive subvented lease provider for Buick and GMC on Feb. 3.
“Cadillac will follow closely after that [in March], then Chevy,” Birch said. “By mid-year, we’ll have full lease exclusivity with all GM brands.”
The decision didn’t sit well with Ally Financial executives. “While we were not surprised by the idea of GM growing their captive, we were surprised that they would exclude any competition in the lease space,” said Michael Carpenter, who retired last month from his CEO post, during Ally’s Jan. 29 earnings call. “And frankly, we don’t see how auto sales are increased by having less options for consumers and dealers.”
Responding during the company’s Feb. 4 earnings call, GM Financial executives said the decision was about customer loyalty, adding that it made sense to keep those customer relationships and data within GM’s control. Keeping the profitability associated with leasing — GM Financial finishing 2014 with less than a 50% share of GM leases — was another factor.
When asked if those same factors would drive GM Financial into the product side, Birch said: “We would expect at some point in our future, and I can’t tell you when, but there’s a natural evolution for those types of products to come back to the finance company.”
More Auto Finance

Interest Rates Further Squeeze Auto Consumers
Last month’s hike and a potential second increase this month add to a growing list of inflation woes that could continue to dent overall car sales.
Read More →
Mind Your Process
Consistent steps taken in various aspects of the F&I office can make valuable differences over time, similar to an outline for a best-selling book.
Read More →
Top Five Credit Application Fraud Flags
Compliance audits regularly reveal bad habits that can lead to fraud charges and should have been stamped out decades ago.
Read More →
More Auto Loans for the Taking in August
Riskier categories were on the uptick for the month as lenders loosened access in several areas while balancing out the exposure in another, Cox Automotive reported.
Read More →
July Was Hot for Auto Borrowers
Credit proved readily available for many, but most loans left buyers in negative territory, Cox Automotive said.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Auto Refi Savings Surge
Consumers with 84-month auto loan terms who refinanced saved the most on monthly payments, according to a new report by auto refinancing provider Caribou.
Read More →
Subaru Enters Lending Business
The automaker follows other brands in adding captive financing in the U.S., and says the move will strengthen its position here.
Read More →
Positive Equity Reaches Record High
Mainstream vehicle owners who bought a car seven years ago are likely to have positive equity when trading in for a new vehicle, according to second-quarter Edmunds data.
Read More →
Dealerships Are Paying the Price for Extended Car Loans
Growing negative-equity scenarios mean such lengthy terms should be addressed in a forward-looking way to make them work for the dealer and the consumer down the road.
Read More →