

Solving Affordability and Negative-Equity Challenges
Facing these realities should be a key strategy for automotive dealers.
Offering affordable payments tied to consumer pay cycles is more than a strategic advantage—it’s a necessity.
Pexels/Jonathan Borba
As the automotive industry evolves, so do the financial challenges faced by both consumers and dealers. Rising vehicle prices and elevated interest rates have pushed monthly car payments to record highs, creating significant affordability barriers for many buyers. With approximately 70% of Americans living paycheck to paycheck, this trend has a direct impact on consumers’ purchasing power and their ability to afford vehicles. To face these challenges, dealerships must embrace more affordable payment options that align with consumer pay cycles, offering a win-win solution for both dealers and customers.
The Paycheck-to-Paycheck Reality
Almost all Americans, 95%, are paid weekly, biweekly, or twice per month. For these consumers, budgeting is often a challenging process that requires them to align the timing of loan and bill payments with their cash flows. Yet traditional monthly car payments don’t always mesh well with weekly, biweekly and twice-per-month pay schedules, leading to increased financial strain, budgeting difficulties, and less ability to purchase vehicles and protection products. By offering payments that match consumers’ pay cycles, dealers can provide easier and more affordable payments for customers.
Affordability Challenges
Today’s vehicle-financing environment is marked by escalating monthly payments, which now average over $740 for new cars and $500 for used vehicles. As affordability remains a top concern, dealers must adapt their offerings to accommodate their buyers and provide more customer-centric solutions.
Negative-Equity Challenges
Today’s vehicle-financing environment is marked by escalating negative equity. According to Edmunds, in 2024, 25% of trade-ins had negative equity. That was up from about 20% in 2023. The average amount owed reached an all-time high of $6,838, while about one in four car owners with negative equity owed more than $10,000.
The Case for Customer-Centric Payments
Offering payments that align with customers’ pay cycles presents several benefits:
1. Enhanced affordability and F&I opportunities: Lower, easier automated payments allow consumers to fit their car payments into their pay cycles more easily, leaving room for additional F&I products. This approach enables customers to better afford protection products, like warranties, gap insurance, and service plans—boosting dealership revenue. Data from dealers show that customers buy 1½ more products per deal with easier payments that match their pay cycles. Further, transactions are faster and more profitable because customers more often accept first-pencil offers from the sales desk when the lower and easier payments that match their pay cycles are offered on first pencil.
2. Reduced negative equity: Affordable, automated payments help customers pay off their loans more quickly, improving equity positions and reducing negative-equity situations. This positions buyers to trade their vehicles sooner and with better equity positions, fostering long-term customer loyalty and repeat business for dealers.
3. Increased customer satisfaction: Offering payments that align with consumers’ pay cycles demonstrates a dealership’s commitment to understanding and addressing their customers’ needs. This not only enhances the buying experience but also builds trust and convenience, critical factors in today’s competitive market.
The Path Forward for Dealers
To implement more affordable weekly, biweekly and semimonthly payment options, dealers should partner with payment providers who understand the value of tailoring financing solutions, and integrate with existing dealer software. Integrating lower and easier payments into existing workflows at the sales desk and in F&I offices is essential for streamlining customer-centric sales presentations that maximize customer satisfaction and profits.
By prioritizing affordability and aligning payments with consumers’ pay cycles, dealerships can better serve customers and improve retention rates.
Conclusion
In an era when affordability challenges dominate the automotive market, dealers must adapt to meet consumer needs. Offering affordable payments tied to consumer pay cycles is more than a strategic advantage—it’s a necessity. This approach not only addresses the economic realities of today’s buyers but also enhances dealership profitability by fostering customer loyalty, boosting F&I product penetration, increasing front gross, and reducing negative equity and trade cycles. By offering flexible payment solutions, dealers can position themselves as true partners in their customers’ buying process and financial success.
David Engelman is CEO of SmartPay, a provider of automated payments that match how consumers get paid and budget and winner of Dealers’ Choice Awards for 17 consecutive years.
EDITOR’S NOTE: This article was authored and edited according to F&I and Showroom editorial standards and style. Opinions expressed may not reflect that of the publication.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →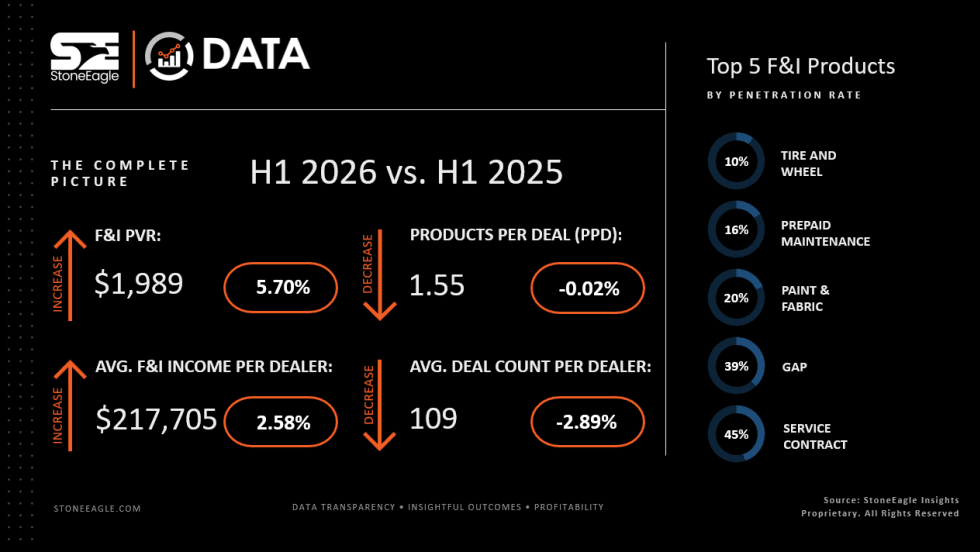
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →