



Powersport's Two-Way Street
A credit card might be the easy way to move a vehicle, but is it right for the customer? F&I expert discusses a better way to get a deal done.
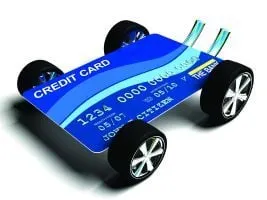
Whether you’re an F&I manager in an auto dealership, RV lot, marine dealership, or powersports store, compliance, rehashing deals, product presentations, paperwork, and customer objections are a fact of life. But one situation unique to powersports F&I is the question of an installment loan vs. a revolving loan.
I don’t believe any F&I manager at a local vehicle franchise, marine dealership or RV lot has to submit credit applications to a lender’s credit card division for the purchase of their units.
This process is a unique situation powersports F&I managers face every day, and has never been addressed by mainstream industry publications until now.
We’ll review the major differences between the two funding sources, the benefits of each to the customer and dealership. We’ll also talk about ways to convert customers to whichever source is most beneficial.
We’ve all seen the TV ads showing bikini-clad women having fun on the water while riding a personal watercraft (PWC). The tag line is something like, “You can be here too for as little as $39 a month!” The fine print on the ad, which is only readable if the freeze frame button on your DVR worked, clearly states all of the required disclaimers, including that “this payment is based on a revolving account and is only for a limited term.” What the disclaimer doesn’t say is after the term expires, the payment can jump to four or five times the original figure. Ads like these are designed to drive customers into the store, and they succeed.
However, this type of advertising makes it difficult to manage the customer’s expectations. That responsibility falls on the F&I manager, who must educate the customer and the sales staff about the difference between an installment loan and a revolving account.
A customer may opt for a low monthly payment on a revolving account, which is equivalent to an interest-only loan. Very little, if any, equity is built during the promotional period. In an installment loan situation, the payment is higher because it includes some principal and interest. However, equity is built at a faster rate. This point is very important to the dealership and customer, as the depreciation and negative equity do have an impact on both sales and ownership.
Two other advantages of the installment sale are the defined term and set interest rate, which tell customers when the loan will be paid off and how much interest they will have paid. In a revolving account, small payments and interest rate fluctuations can result in a protracted payment process. That means the customer can still be paying for that $6,000 PWC eight or nine years from the time of purchase.
If you think that’s an exaggeration, then go to www.bankrate.com and use Website’s payment calculator. Type in a $6,000 loan amount at a 10-percent rate, with a 60-month term. Then click on the amortization table button. The result is a payment of $127.48 per month and a total interest paid of $1,648.94.
Now use the same loan amount and interest rate and try to get the payment down to $39 by only changing the term. I gave up at 100 years and only got the payment down to $50.
Yes, this is an extreme example, but taking customers through these steps will have a greater impact than any word track you could possibly use. This process allows them to see the different inner workings of both loan structures. This should also prove to the customer that you, the F&I professional, are looking out for his or her best interests. It should also demonstrate to your owner that you are looking out for the best interests of the dealership as well.
The installment sale is a win-win situation for you, the dealership and the customer. This process will generate more participation money for you and the dealership. It will also increase the customer satisfaction index (CSI) scores and ensure future business will have trade-ins with little or no negative equity.
The installment sale may become your go-to loan, but don’t forget the revolving account does have a place in every powersports F&I office. F&I managers often encounter limitations imposed on installment loan approvals and the revolving loan can be used to fund most of the protection products we sell. There is nothing wrong with funding the unit and GAP on the installment contract and then funding the service contract and tire-and-wheel products on a revolving account. Just make sure the customer is aware he or she will have two accounts and two separate payments, not just one.
Kevin Burke is the regional manager for UDS PowerSports in Clearwater, Fla.
More Auto Finance
More Auto Loans for the Taking in August
Riskier categories were on the uptick for the month as lenders loosened access in several areas while balancing out the exposure in another, Cox Automotive reported.
Read More →
July Was Hot for Auto Borrowers
Credit proved readily available for many, but most loans left buyers in negative territory, Cox Automotive said.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Auto Refi Savings Surge
Consumers with 84-month auto loan terms who refinanced saved the most on monthly payments, according to a new report by auto refinancing provider Caribou.
Read More →
Subaru Enters Lending Business
The automaker follows other brands in adding captive financing in the U.S., and says the move will strengthen its position here.
Read More →
Positive Equity Reaches Record High
Mainstream vehicle owners who bought a car seven years ago are likely to have positive equity when trading in for a new vehicle, according to second-quarter Edmunds data.
Read More →
Dealerships Are Paying the Price for Extended Car Loans
Growing negative-equity scenarios mean such lengthy terms should be addressed in a forward-looking way to make them work for the dealer and the consumer down the road.
Read More →
Trade-Ins in Negative Equity Reach New Heights
As such trade-ins rise in frequency, so do monthly loan payment amounts and interest rates, according to second-quarter data compiled by Edmunds.
Read More →
Auto Credit Plentiful
June numbers show lenders are readily granting access, including to risky borrowers, as consumers leverage themselves to take on high prices.
Read More →
Automotive Consumers Sink Further in Debt
Most financing metrics hit records in the second quarter as more buyers locked themselves into long terms and high monthly payments.
Read More →