



Cox Automotive: Wholesale Used-Vehicle Prices Unchanged in First Half of June From Seasonal Adjustment
Wholesale used-vehicle prices (on a mix-, mileage-, and seasonally adjusted basis) were essentially unchanged from May after the first 15 days of June.

Wholesale used-vehicle prices (on a mix-, mileage-, and seasonally adjusted basis) were essentially unchanged from May after the first 15 days of June.
Wholesale used-vehicle prices (on a mix-, mileage-, and seasonally adjusted basis) were essentially unchanged from May after the first 15 days of June. This kept the Manheim Used Vehicle Value Index at 222.7, which was up 11.1% from June 2021. The non-adjusted price change in the first half of June was a decrease of 0.3% compared to May, leaving the unadjusted average price up 12.4% year over year.
The last full two weeks covered the end of May, the Memorial Day holiday, and only the first 11 days of June, so the weekly trends were not as aligned with the half-month performance as is typically the case. Over the last two weeks, Manheim Market Report (MMR) prices saw accelerating declines. Over that time, the Three-Year-Old MMR Index, which represents the largest model-year cohort at auction, experienced a 0.6% cumulative increase. Over the first 15 days of June, MMR Retention, which is the average difference in price relative to current MMR, averaged 98.8%, which indicates that valuation models are slightly ahead of market prices. The average daily sales conversion rate of 53.1% in the first half of June declined relative to May’s daily average of 55.3% and has been lower than the typical conversion rate for this time of year. The latest trends in the key indicators suggest wholesale used-vehicle values should see declines in the second half of the month.
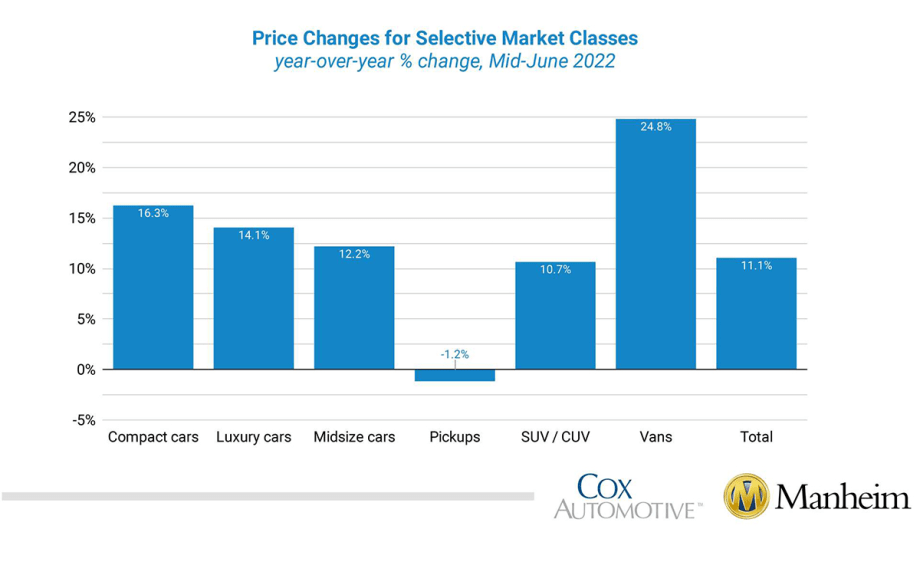
Most major market segments saw seasonally adjusted prices that were higher year over year in the first half of June. Pickups were the exception with a 1.2% decline year over year. Vans had the largest increase at 24.8%, and both non-luxury car segments outpaced the overall industry in seasonally adjusted year-over-year gains. Compared to May, most major segments saw lower performance, except for compact and full-size cars, up 0.5% and 19.9%, respectively. The seasonal adjustment drove the declines, with SUVs having no change from May, while midsize cars and pickups dropped 1.1%.
Retail and wholesale at normal levels in first half of June. Using estimates based on vAuto data as of June 13, used retail days’ supply was 45 days, which was down one day from the end of May. Days’ supply was up seven days year over year. Leveraging Manheim sales and inventory data, we estimate that wholesale supply ended May at 24 days, down one day from the end of April but up five days year over year. As of June 15, wholesale supply was at 25 days, up one day from the end of May and up five days year over year.
Rental risk prices increase. The average price for rental risk units sold at auction in the first 15 days of June was up 30.3% year over year. Rental risk prices were up 1.2% compared to the full month of May. Average mileage for rental risk units in the first half of June (at 59,400 miles) was down 31.6% compared to a year ago and down 6.5% month over month.
Consumer Sentiment declines to start June. The initial June reading on Consumer Sentiment from the University of Michigan declined 14% to 50.2, which was a record low for the index. Consumers’ views of both current conditions and future expectations declined substantially, and the expected inflation rate increased to the highest level since 2008. Consumers’ views of buying conditions for vehicles declined to the lowest reading in the history of the survey dating back to 1978. The daily index of consumer sentiment from Morning Consult also declined in the first half of June. As of June 15, the index was down 5.1% compared to May 31 and was at a new low for the index.
Originally posted on Auto Dealer Today
More Auto Finance

Interest Rates Further Squeeze Auto Consumers
Last month’s hike and a potential second increase this month add to a growing list of inflation woes that could continue to dent overall car sales.
Read More →
Mind Your Process
Consistent steps taken in various aspects of the F&I office can make valuable differences over time, similar to an outline for a best-selling book.
Read More →
Top Five Credit Application Fraud Flags
Compliance audits regularly reveal bad habits that can lead to fraud charges and should have been stamped out decades ago.
Read More →
More Auto Loans for the Taking in August
Riskier categories were on the uptick for the month as lenders loosened access in several areas while balancing out the exposure in another, Cox Automotive reported.
Read More →
July Was Hot for Auto Borrowers
Credit proved readily available for many, but most loans left buyers in negative territory, Cox Automotive said.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Auto Refi Savings Surge
Consumers with 84-month auto loan terms who refinanced saved the most on monthly payments, according to a new report by auto refinancing provider Caribou.
Read More →
Subaru Enters Lending Business
The automaker follows other brands in adding captive financing in the U.S., and says the move will strengthen its position here.
Read More →
Positive Equity Reaches Record High
Mainstream vehicle owners who bought a car seven years ago are likely to have positive equity when trading in for a new vehicle, according to second-quarter Edmunds data.
Read More →
Dealerships Are Paying the Price for Extended Car Loans
Growing negative-equity scenarios mean such lengthy terms should be addressed in a forward-looking way to make them work for the dealer and the consumer down the road.
Read More →