



Experian: Americans Borrow Record Amounts for Auto Purchases in Q1
The dream of owning a new vehicle is becoming more elusive for the average American consumer, with the average amount financed and monthly payment for a new vehicle climbing to record highs of $31,455 and $523, respectively.

SCHAUMBURG, Ill. — The expectation is that new-vehicle sales will continue their downward trend. Experian’s State of the Automotive Finance Market for the first quarter may reveal the reason.
According to the report, loan amounts, monthly payments and interest rates for new vehicles continue to rise, with the average amount financed on a new vehicle increasing $921 form the year-ago quarter to a record $31,455. The average monthly payment on a new vehicle also hit a new record, increasing $15 from the prior-year period to $523. The average interest rate for a new vehicle in the first quarter was 5.17%.
"The dream of owning a new vehicle is becoming more elusive to the average American,” said Melinda Zabritski, Experian's senior director of automotive financial solutions. "To reverse the trend, dealers and lenders need to better understand the data and explore different options to make new vehicle ownership accessible and appealing."
The report also shows that loan terms for new vehicles have also increased, climbing just above 69 months during the quarter. While 72-month loans remain the most common loan term, more new loans have spilled into the 85- to 96-month bucket.
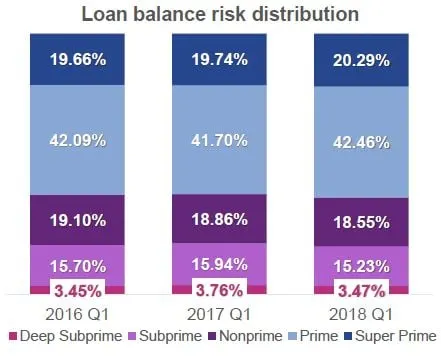
The population segments most impacted, according to Experian, are subprime and deep subprime consumers, with the percentage of new-vehicle loans made to consumers who fall in those credit spectrums falling 8.4% and 14.1%, respectively. Conversely, the percentage of new-vehicle loans extended to consumers with prime and superprime credit climbing to 73.4% — the highest first quarter level since 2012 and a sign that some finance sources have become more risk-averse.
Despite those increases and the reduction of credit extended to riskier borrowers, first-quarter data reveals a strong and improving auto finance market. The percentage of loans 30 days delinquent, for instance, dropped 3.1% from the year-ago period to 1.90%, while 60-day delinquencies remained flat at 0.67%.
"Traditionally, lenders' risk tolerance has swung back and forth like a pendulum, and right now we're seeing a more risk-averse side. But if payments continue to improve, we could see credit standards loosen," Zabritski said. "The more insight lenders have into consumer credit behavior, the better decisions they can make."
According to the report, outstanding auto loan balances reached a record high of $1.108 trillion, with credit unions showing the highest growth in terms of market share. The segment grew its share 6.9% from a year ago to 21.3%.
The average credit score for a new-vehicle loan during the quarter rose to 716, while the average credit score for a used-vehicle loan rose to 655. Additionally, the average amount financed for a used vehicle reached a new record high of $19,536.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →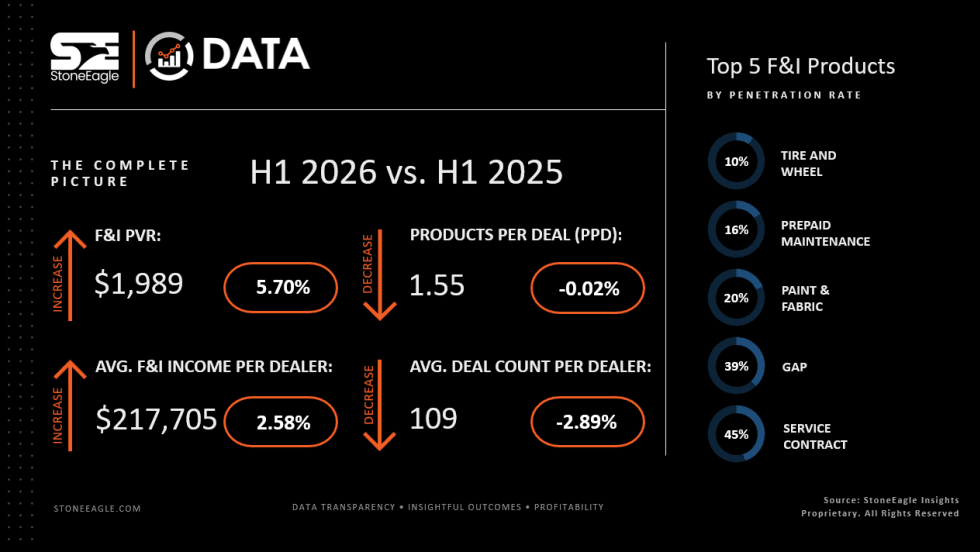
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →