

GOA Says Congress Can Review CFPB’s Guidance on Dealer Participation
The Government Accountability Office said on Tuesday that the bureau’s March 2013 bulletin on dealer participation falls under the Congressional Review Act, a decision that clears the way for the Republican-controlled Congress to repeal the bureau’s controversial guidance.

WASHINGTON, D.C. — The Government Accountability Office (GOA) said on Tuesday that the Consumer Financial Protection Bureau’s controversial March 2013 guidance on dealer participation falls under the Congressional Review Act and should have been submitted to Congress and the Comptroller General for review before it took effect.
The GOA’s conclusion, which was issued in response to Sen. Pat Toomey (R-Pa.) March 31 request that it review whether the bureau’s guidance falls under the CRA, sets the table for the Republican-controlled Congress to pass a joint resolution of disapproval under the CRA to repeal the bureau’s auto finance guidance — a process similar to the one used to repeal the bureau’s rule on forced arbitration.
“The CFPB claims that the bulletin is the type of general statement of policy that is not a rule under CRA. However … CRA requirements apply to general statements of policy, which, by definition, are not legally binding,” GOA General Counsel Thomas Armstrong wrote in his seven-page response. “The Supreme Court has described ‘general statements of policy’ as ‘statements issued by an agency to advise the public prospectively of the manner in which the agency proposes to exercise a discretionary power.’
“In other words, as stated by the D.C. Circuit Court of Appeal in Pacific Gas & Electric Company v. Federal Power Commission, a statement of policy announces the agency’s tentative intentions for the future.”
In its five-page fair lending guidance, the CFPB said it would hold lenders active in the indirect auto finance channel liable for unlawful, discriminatory pricing. It alleged that bank policies which allow auto dealers to mark up the interest rates on retail installment sale transactions as compensation for services rendered create a significant risk of unintentional, disparate impact discrimination.
The bulletin goes on to state that lenders operating in the indirect auto finance channel “should take steps to ensure that they are operating in compliance with the [Equal Credit Opportunity Act and Regulation B as applied to dealer markup and compensation policies.” It then listed a variety of steps and tools they could employ to address the bureau’s stated fair lending risks,” including “eliminating dealer discretion to mark up buy rates and fairly compensate dealers using another mechanism, such as a flat fee per transaction, that does not result in discrimination.”
Auto finance trade groups have argued that the bureau used its guidance to indirectly regulate the activities of dealers, which are exempted from the bureau’s oversight under the Dodd-Frank Act. Since issuing its guidance, the bureau has imposed millions of dollars in fines on auto finance sources, including Ally Financial, American Honda Finance Corp, and Fifth Third Bank.
Congress has attempted to kill the bureau’s guidance through the legislative route. In November 2015, for instance, the House of Representative approved the Reforming CFPB Indirect Auto Finance Guidance Act by a 332-96 vote. The bill, however, was not acted upon by the Senate before the end of the 114th Congress.
When it initially issued its guidance, the bureau argued that because it had no legal effect on regulated entities, the CRA does not apply. The GOA, however, stated in its response that the bulletin “fits squarely within the Supreme Court’s definition of a statement of policy” because it provides information on the manner in which the bureau planned to exercise its discretionary enforcement power.
And according to the GOA, the CRA “establishes special expedited procedures under which Congress may pass a joint resolution of disapproval that, if enacted into law, overturns the rule.” In a statement posted on his website, Sen. Toomey said that’s exactly what he intends to do.
“GOA’s decision makes clear that the CFPB’s backdoor effort to regulate auto loans, which was based on a dubious legal justification, did not comply with the Congressional Review Act,” said Sen. Toomey, who requested that the agency review whether the bureau’s guidance fell under the CRA in March 2017. “GOA’s decision is an important reminder that agencies have a responsibility to live up to their obligations under the law. When they don’t, Congress should hold them accountable.
“I intend to do everything in my power to repeal this ill-conceived rule using the Congressional Review Act.”
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →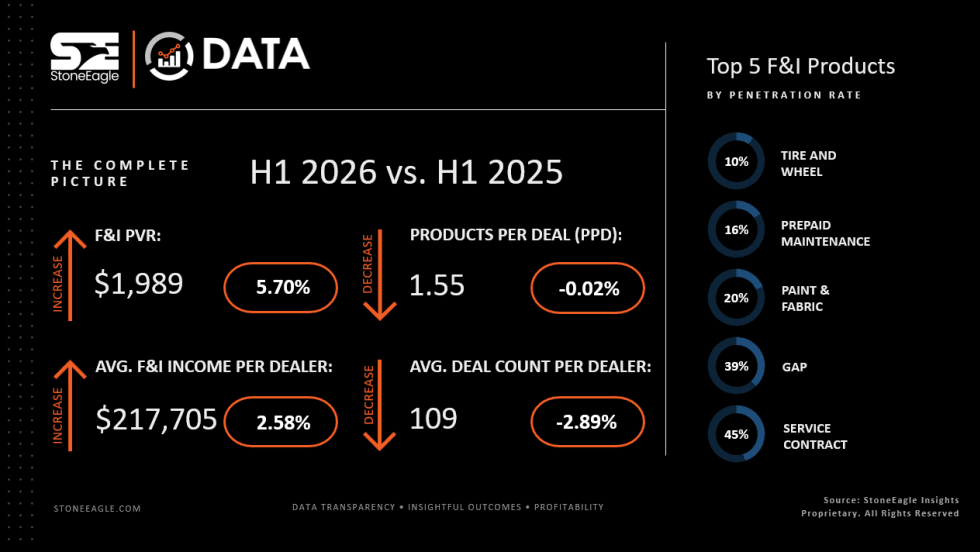
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →