

J.D. Power: Dealership Experience Impacts Lender Selection
J.D. Power released its annual report card on the experience finance sources deliver to customers. It highlights the link between the dealership experience and the finance source’s ability to retain customers.
WESTLAKE VILLAGE, Calif. — J.D. Power and Associates’ 2012 Consumer Financing Satisfaction Study, released today, highlighted the strong link between what happens at the dealership and the auto finance source’s ability to retain its customers.
The dealer-to-lender link was much stronger than the lender-to-dealer link, as the study found a minimal relationship between how a lender services a customer’s loan and the dealership’s ability to retain customers.
“While a similar relationship does not exist with respect to considering the same dealership, finance providers may still influence dealer consideration by ensuring efficient approval processes and knowledgeable staff,” said Lisa Stimac, account director of automotive finance at J.D. Power and Associates. “Most consumers just want the vehicle-buying process to be simple. Financing is a tough area to simplify, but by providing seamless, fast service throughout the loan or lease period, financing providers increase their chances of being re-selected and building brand loyalty.”
The role dealers play in the lender-to-consumer relationship was also highlighted in the section covering the top issues consumers have with finance sources. Dealership-related issues and complaints tied with collections issues as the fourth highest reason for complaints. The Top three reasons for problems were issues with posting a payment, receiving statements late or not at all, and issues with late fees.
“What we see a lot of times is [consumers] don’t separate automotive lenders from dealers, especially when it’s a captive,” said David Lo, director of financial services. “And if you were to ask a customer out right what their rate is, they’re not going to be about to answer that. What happens is there is a disconnect between what they got because of their credit and what was promoted.”
The study also noted that the best practices in auto finance servicing are related to problem prevention. These practices include providing service alerts, reminding customers of a payment or confirming when a payment has been made, providing accurate and informative billing information, and offering alternative, easy-to-use methods for reviewing account information.
“Addressing and resolving problems that do occur serve the dual purpose of increasing customer satisfaction and minimizing the number of interactions with the lender, which takes time and resources,” Stimac said. “Of course, when a customer experiences a problem, resolving it quickly and efficiently is critical to recover the lost goodwill from problems in the first place.”
The study measured customer satisfaction in four key factors of the new-vehicle financing experience: billing and payment; interest rate/monthly payment; website; and phone contact. The study was conducted across four consumer vehicle financing segments: mass market loan; mass market lease; luxury loan; and luxury lease.
Consumer Financing Segment Rankings
Mass Market Loan Segment: Volkswagen Credit (865) ranks highest, followed by Mazda Capital Services (844) and Honda Financial Services (843).
Mass Market Lease Segment: Ford Credit (827) ranks highest in the segment, followed by Volkswagen Credit (816) and Honda Financial Services (802).
Luxury Loan Segment: Mercedes-Benz Financial Services ranks highest with a score of 853 (on a 1,000-point scale), followed closely by Acura Financial Services with a score of 852. BMW Financial Services ranks third with a score 848.
Luxury Lease Segment: Lincoln Automotive Financial Services ranks highest with a score of 826. Following in the rankings are Lexus Financial Services (808) and Mercedes-Benz Financial Services (806).
The 2012 Consumer Financing Satisfaction Study is based on responses from 11,259 new-vehicle purchasers or lessees who completed a vehicle loan or lease transaction between June 2011 and May 2012. The study was fielded between August and October 2012.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →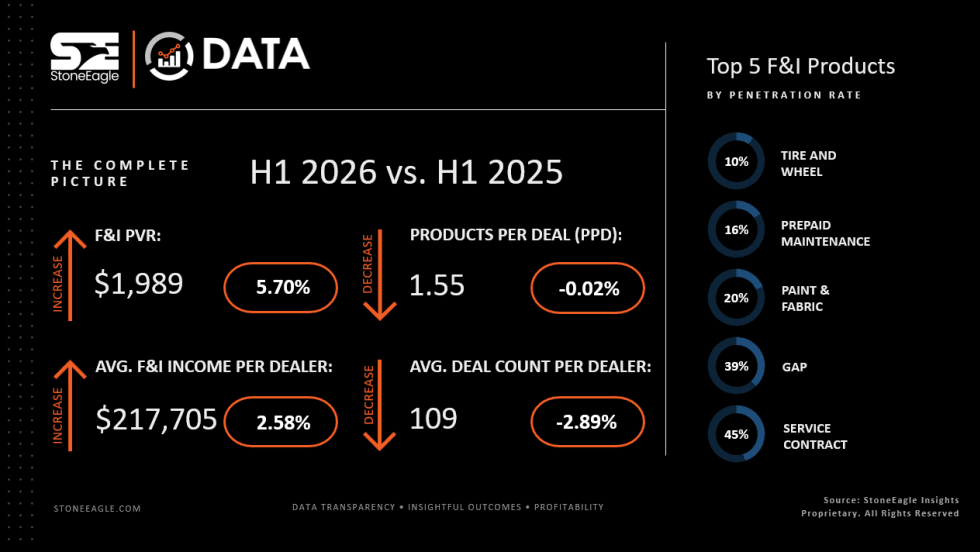
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →