

KBB: New-Car Sales Expected to Dip Nearly 1% in August
New-vehicle sales are expected to decrease 0.7% year-over-year to a total of 1.49 million units, resulting in an estimated 16.5 million seasonally adjusted annual rate, according to a forecast from Kelley Blue Book.
IRVINE, Calif. — New-vehicle sales are expected to decrease 0.7% year-over-year to a total of 1.49 million units, resulting in an estimated 16.5 million seasonally adjusted annual rate (SAAR), according to Kelley Blue Book.
Although sales are down from a raw volume perspective, they remain up slightly after adjusting for the difference in selling days in August 2014 versus August 2013. The SAAR for August 2014 is up from 15.9 million in August 2013 and up from 16.4 million in June 2014.
“Although growth has slowed, sales remain steady and on pace to end the year strong,” said Alec Gutierrez, senior analyst for Kelley Blue Book. “Growth is expected to continue to soften, so we wouldn’t be surprised to see automakers increase their incentive spending. Spending was restrained for the first part of the year, and has crawled upward in recent months. Sales also will be boosted by the Labor Day weekend, which is traditionally one of the strongest weekends of the year for vehicle sales.”
KBB’s Estimated August 2014 Sales Forecast also shows that during the month, retail sales are expected to account for 89% of volume.
According to KBB, the Chrysler Group continues its impressive run in 2014 with double-digit growth in August. The Jeep brand has been especially strong, becoming Chrysler Group’s highest selling and the industry’s fastest growing brand. Much of Jeep’s success is due to the Cherokee, which launched late last year. Due to one fewer selling day this year, KBB anticipates most of the major manufacturers to remain flat or post minimal declines year-over-year.
Both compact and mid-size SUVs/crossovers continued to be the strongest vehicle categories in August. This year, compact and mid-size SUVs/crossovers are responsible for nearly 60% of the industry’s growth, as two of the fastest selling segments. Compact SUVs/crossovers average 49 days to turn, while mid-size SUVs/crossovers average 61 days, both just slightly higher than this time last year.
“The mid-size car segment continues to lose steam this year,” Gutierrez said. “Sales on the year are down 2%, average transaction prices are down 1%, while incentive spending is up nearly $500 per unit. Recently redesigned models such as the Hyundai Sonata and Chrysler 200 will face challenges in this highly competitive segment.”
Sales Volume 1 | Market Share 2 | |||||
Manufacturer | Aug-14 | Aug-13 | YOY % | Aug-14 | Aug-13 | YOY |
General Motors (Buick, Cadillac, Chevrolet, GMC) | 273,000 | 275,847 | -1.0% | 18.3% | 18.4% | -0.1% |
Toyota Motor Company (Lexus, Scion, Toyota) | 221,000 | 231,537 | -4.6% | 14.8% | 15.4% | -0.6% |
Ford Motor Company (Ford, Lincoln) | 217,000 | 220,404 | -1.5% | 14.6% | 14.7% | -0.1% |
Chrysler Group (Chrysler, Dodge, Jeep, RAM) | 184,000 | 165,552 | 11.1% | 12.3% | 11.0% | 1.3% |
American Honda (Acura, Honda) | 153,000 | 166,432 | -8.1% | 10.3% | 11.1% | -0.8% |
Nissan North America (Infiniti, Nissan) | 122,000 | 120,498 | 1.2% | 8.2% | 8.0% | 0.2% |
Hyundai-Kia | 117,000 | 118,126 | -1.0% | 7.9% | 7.9% | 0.0% |
Volkswagen Group (Audi, Volkswagen, Porsche) | 51,000 | 57,674 | -11.6% | 3.4% | 3.8% | -0.4% |
Total 3 | 1,490,000 | 1,500,387 | -0.7% | - | - | - |
1 Historical data from OEM sales announcements | ||||||
2 Kelley Blue Book Automotive Insights | ||||||
3 Includes brands not shown | ||||||
Sales Volume 1 | Market Share | |||||
Segment | Aug-14 | Aug-13 | YOY % | Aug-14 | Aug-13 | YOY |
Compact Car | 221,000 | 225,457 | -2.0% | 14.8% | 15.0% | -0.2% |
Mid-Size Car | 215,000 | 222,870 | -3.5% | 14.4% | 14.9% | -0.4% |
Compact SUV/Crossover | 193,000 | 181,714 | 6.2% | 13.0% | 12.1% | 0.8% |
Full-Size Pickup Truck | 175,000 | 180,076 | -2.8% | 11.7% | 12.0% | -0.3% |
Entry-level Luxury Car | 72,000 | 78,055 | -7.8% | 4.8% | 5.2% | -0.4% |
Total 2 | 1,490,000 | 1,500,387 | -0.7% | - | - | - |
1 Kelley Blue Book Automotive Insights | ||||||
2 Includes segments not shown | ||||||
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →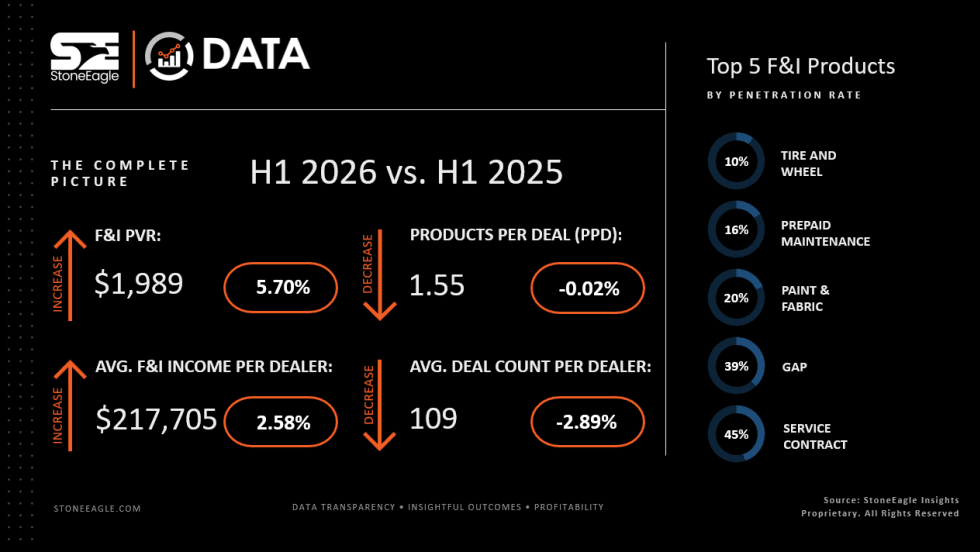
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →