



Slight Growth in Loan Originations, Reports U.S. Treasury
The U.S. Treasury Department's monthly bank lending survey found that outstanding loan balances were flat in May, but also revealed modest growth in new-loan originations among the 21 banks surveyed.
The U.S. Treasury Department’s monthly bank lending survey found that outstanding loan balances were flat in May, but also revealed modest growth in new-loan originations among the 21 banks surveyed.
Data was acquired from the top 21 recipients of government investments through the Capital Purchase Program (CPP).
The economic environment in May, against which banks reported their lending and intermediation activities, experienced further deterioration, despite modest improvement in a number of indicators. That weakness is feeding into the financial system and credit markets and weakening overall demand for credit by consumers and businesses.
The lending survey results show that total outstanding consumer loans (the total of outstanding loans in all four consumer categories – first lien mortgages, home equity lines of credit, credit card loans, and other consumer loans) of all respondents were flat in May. Households are facing growing pressures from a weakening labor market and the recent declines in their wealth. In this context, consumers focused on paying down debt, driving the decreases in outstanding balances held by major banks.
As with consumer loans, the outstanding stock of total commercial and industrial (C&I) loans was flat in May. Banks reported that demand by businesses for C&I loans was well below normal levels. This decline was attributed to lower demand among businesses for capital expenditure loans and for loans to finance acquisitions, plants, equipment, inventories and accounts receivables. As firms continue to downsize, cut costs, and reduce inventories, banks predict that lower demand will persist through the second quarter of 2009.
In the commercial real estate (CRE) sector, the May survey results point to continuing poor market conditions and general caution by businesses. CRE loan balances at these 21 banks fell by 1 percent, and banks reported that demand for CRE loans remained well below normal levels as businesses continue to focus on strengthening their balance sheets, reserving for future losses, and downsizing. Additionally, the lower demand for new loans reflected a surplus in the market, as the supply of office space has increased due to firms downsizing and office vacancies rising.
Total originations of loans by all respondents rose in four categories, specifically: mortgages, credit card loans, commercial real estate renewals and commercial real estate new commitments. Total originations fell in the following three loan categories: home equity lines of credit, other consumer lending products, and commercial and industrial renewals, and were flat in one loan category, commercial and industrial new commitments. Total originations of all loans (by all 21 respondents) increased by 1 percent. Fourteen banks posted increases in originations, and seven banks posted declines.
Small business lending showed growth in May. The total outstanding balance of small business loans increased by 1 percent in May, while total small business loan originations increased by 7 percent.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →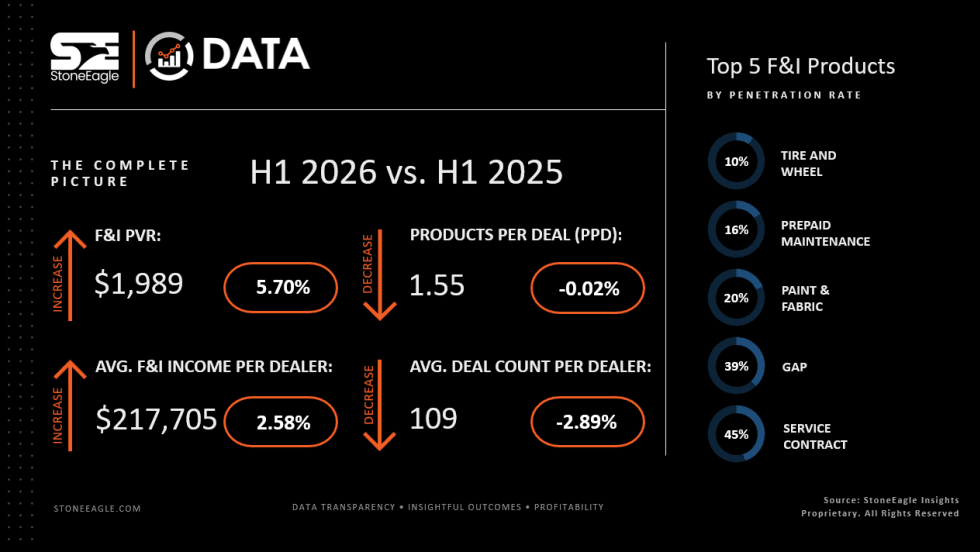
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →