

The CFPB Puts Debt Collectors on Notice
The CFPB is now taking consumer complaints regarding debt collectors. The bureau also warned firms they will be held accountable for unlawful debt-collection activities.
WASHINGTON, D.C. — This week, the Consumer Financial Protection Bureau (CFPB) put companies on notice through bulletins advising that all companies under bureau’s jurisdiction will be held accountable for unlawful debt-collection activities. The CFPB also announced it is now accepting complaints related to debt collectors. It also published action letters consumers can use when corresponding with debt collectors.
“These bulletins make clear that it doesn’t matter who is collecting the debt — unfair, deceptive, or abusive practices are illegal,” said CFPB Director Richard Cordray at a field hearing in Portland, Maine. “Consumers need options to help them secure fair and respectful treatment from those debt collectors that fail to abide by the law. They can protect themselves by using our action letters to communicate with debt collectors and by submitting a complaint to us if they believe they are harmed by illegal conduct.”
Debt collection is a multi-billion dollar industry. It is estimated that there are more than 4,500 debt collection firms in the U.S. According to the Federal Reserve Bank of New York, as of the first quarter of this year, almost 15 percent of all credit reports — covering an estimated 30 million consumers — show collection items from debt collection. These consumers had at least one debt in collections for amounts that averaged about $1,400.
The bureau also published two bulletins on debt collection this week. The first makes clear that any entity subject to the Consumer Financial Protection Act of 2010, whether a third-party collector or a creditor collecting its own debts, can be held accountable for any unfair, deceptive, or abusive practices in collecting a consumer’s debts. The second warns companies to avoid deceptive statements concerning the impact of paying a debt on a consumer’s credit score, credit report, or creditworthiness.
According to the first bulletin the following practices, among others, may be illegal:
• Threatening action that the debt collector does not have the authority to pursue: Debt collectors and creditors should not make false threats of lawsuits, arrest, prosecution, or imprisonment for non-payment of debt.
• Falsely representing the character, amount or legal status of the debt: Debt collectors and creditors should not falsely represent who owns the debt, the amount of debt that is owed, or the debt’s legal status.
• Misrepresenting that a consumer’s debt would be waived or forgiven: Debt collectors and creditors should not misrepresent that a debt would be waived or forgiven if a consumer accepted a settlement offer when the company is not, in fact, forgiving or waiving the debt.
• Failing to properly post payments or credit to a consumer’s account with payments: Debt collectors and creditors should not fail to properly post payments or credit to a consumer’s account and then charge late fees to that customer if the customer paid on time.
The CFPB is also releasing a second bulletin today that warns companies about statements they make about how paying a debt will affect a consumer’s credit score, credit report, or creditworthiness. The bureau is concerned that some of these statements — like telling consumers that paying a debt would improve their credit score — may be deceptive. The bulletin highlights examples of potentially deceptive claims debt collectors may be making to consumers about their credit reports and credit scores.
The CFPB also announced it is now collecting complaints about debt collection as of this week. The CFPB can accept complaints from consumers experiencing debt collection problems related to any consumer debt, including credit card debt, mortgages, auto loans, medical bills, and student loans.
The CFPB has been taking consumer complaints since launching on July 21, 2011, beginning with credit card complaints. The Bureau requests that all companies respond to complaints within 15 days with the steps they have taken or plan to take, and expects all but the most complicated complaints to be closed in 60 days. Consumers are given a tracking number after submitting a complaint and can check the status of their complaint by logging on to the CFPB website.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →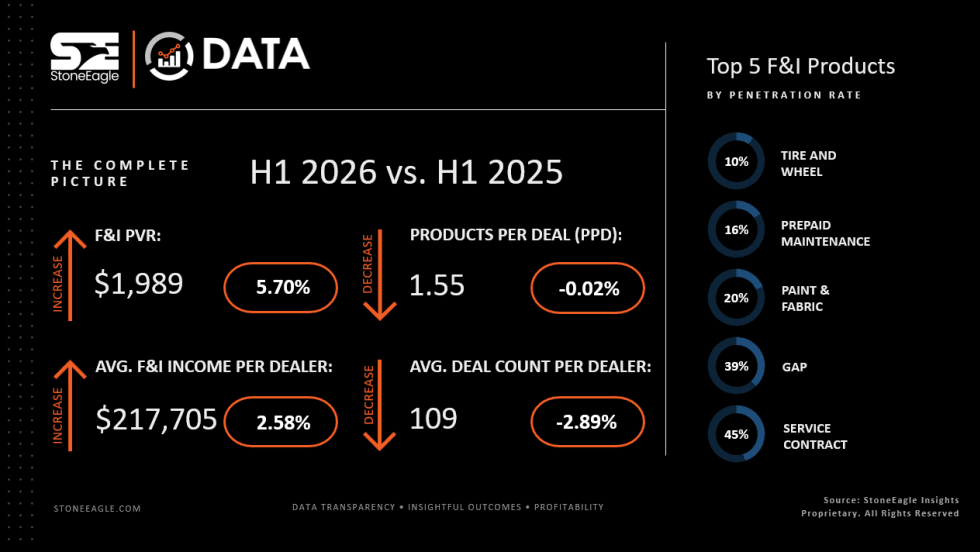
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →