



5 Reasons Not to Stretch Term
With consumers shopping for the right monthly payment, it’s no wonder loans are stretching out. But is it right for the industry? Market insider takes a look at the impacts from the lender’s viewpoint.

The auto finance industry continues to slide down the slippery slope of booking more and more loans with longer-term maturities. What’s worse is it’s happening across the entire credit spectrum. The 72-month term is quickly replacing the 60-month term for both new and used vehicles. The question is how this current situation will impact the automotive retail industry.
According to the 2007 Automobile Finance Study from the Consumer Bankers Association (CBA), 58 percent of new-vehicle loans had terms greater than 60 months. That has grown from 55 percent last year and 45 percent the year before. Used vehicle loans are no exception, as the study showed 48 percent of these loan terms were greater than 60 months, up from 40 percent reported in the 2006 study.
The impacts of this growing trend are many. On the lender side, the repercussions include slower repayment; greater severity of loss on repossessions; longer negative equity with a greater chance of the customer walking away from the loan; slower future vehicle sales for the automotive industry as a whole; reduced future down payments; and lower overall credit standards. So let’s take a look at each issue.
1. Slower repayment of the loan
The 2007 CBA Automobile Finance Study also revealed that, on average, the size of new- and used-vehicle loans remained relatively flat compared to the 2006 study results, with used-vehicle loans increasing slightly and new-vehicle loans showing a slight decrease. This puts the spotlight on terms, which saw significant changes between this year and last. The problem here is that lenders must wait longer to be repaid the principle loan balance advanced at the time of origination.
2. Increase in severity of expected loss
The next area of caution for lenders, and probably the biggest risk a lender incurs, is the increase in severity of expected loss at time of repossession. The probability of default due to longer terms naturally goes up, as does the expected loss at the time of default. For example, let’s take a $25,000 loan with a 10-percent interest rate and 72-month term. A repossession of that vehicle and a charge-off after 24 monthly payments will generate approximately $1,750 in additional losses when compared to a 60-month loan. This may not sound like much, but it quickly adds up when multiplied by a lender’s repossessions.
3. Longer negative equity
Similar to the increase in loss severity are the inherent risks associated with an increase in duration and exposure a lender must endure while his or her collateral possesses negative equity. As the vehicle depreciates during the life of the loan, the principle pay-down takes much longer to catch up to the actual wholesale value of the vehicle. The result is a longer and more severe period of negative equity that increases the loss in the event of a repossession or charge-off. The danger for lenders (in any negative equity situation) is that negotiating power in a default scenario is greatly reduced, increasing the chance that a customer may just walk away from the loan.[PAGEBREAK]
Longer periods of negative equity also affect future down payments and future vehicle sales as a whole. With longer terms, a customer cannot leverage the equity in his or her current vehicle as a trade-in for down payment toward a new one. This forces some customers to hold on to their current vehicles longer than they have in the past. Recent studies have shown that the average trade-in age is increasing (5.4 years in 2006 vs. 5.2 in 2004). Vehicle sales have already shown a decline from 2005 to 2006 due to the slumping housing market, rising interest rates, higher gas prices and decreased demand for trucks and SUVs. In the end, longer loan maturities will only add to the existing challenges dealers face to sell more vehicles.
4. Lower Credit Standards
Lower credit standards will also begin to emerge as a result of longer-term maturities. In some cases, this is already happening. Lower overall credit standards are showing up with the increase of used vehicles. It’s also being seen with nonprime and high-risk (i.e., subprime) customers who are obtaining loans with terms of 60 months or greater. At the time of origination, an underwriter may approve a longer-term loan to reduce a borrower’s payment-to-income (PTI) ratio so they stay within the credit policy; however, the inherent risks in this practice are coming to fruition.
5. Looking Ahead
To manage the negative impacts from longer-term maturities, lenders must take a good look at internal processes and business objectives. This can be done by asking some key questions, such as: Are we effectively using predictive analytics and business intelligence as a part of credit decisions and pricing models to mitigate risk? Are the right collections, remarketing and recovery strategies in place to minimize losses on the back-end? Or, are we simply trying to keep up with the competition?
There are options for managing risks from longer-term maturities — and each solution may vary based on the unique needs of the lender. The institutions that conduct a thorough self-examination and effectively leverage internal tools and intelligence will be the most successful at mitigating these risks.
Walter Cunningham is president of BenchMark Consulting International, a firm that conducts industry benchmarks and business intelligence service. BenchMark has collected performance data representing more than 50 business processes obtained through detailed analysis inside more than 150 different banks and financial service organizations, including all 14 automobile captives.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →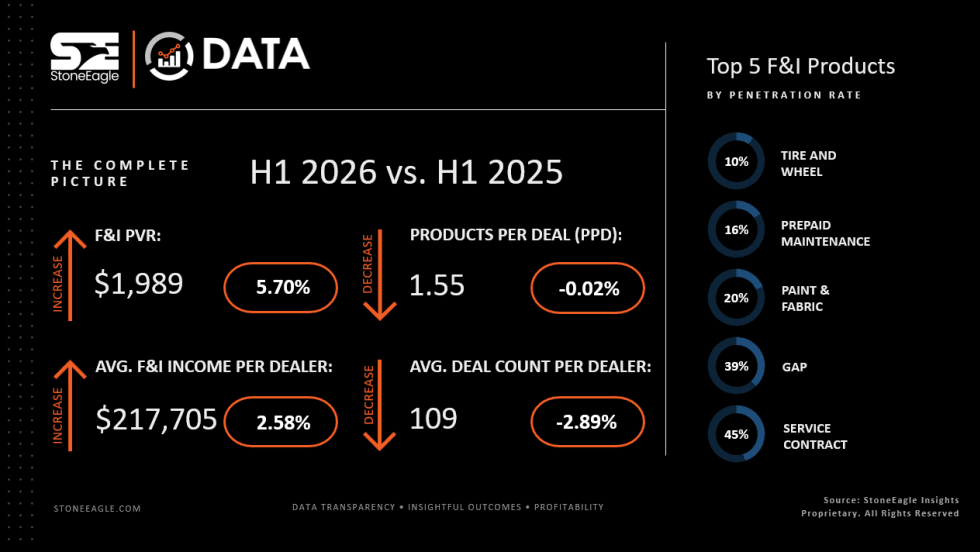
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →