



Don't Be a Target
The new U.S. consumer financial watchdog has pledged to aggressively pursue discriminatory lending practices. Legal insider provides recommendations on how to ensure your store isn’t caught in the crossfire.
Randy Henrick
There is a new regulatory sheriff in town that dealers need to be aware of and ready for. That new law enforcer is the Consumer Financial Protection Bureau (CFPB), and it is targeting credit discrimination.
The bureau, created by the Dodd-Frank Act of 2010, will initially approach lenders to look at their entire portfolio of loans — including mortgages, student loans, credit cards, and even auto loans — to weed out any unusual patterns or incidents of credit discrimination to protected classes of persons under the Equal Credit Opportunity Act (ECOA).
Enacted in 1974, the ECOA prohibits discrimination in credit terms on the basis of gender, marital status, race, color, religion, national origin or amount of income derived from any public assistance program. Lender investigations are already underway and could trickle down to the lenders’ partners, including auto dealers, should the CFPB uncover any questionable recurring incidents.
When investigating lenders, the CFPB plans to follow the ECOA doctrine of "disparate impact," which holds that practices appearing facially neutral (such as a dealer’s ability to mark up the buy rate) may be considered discriminatory and illegal if those practices have a disproportionate adverse impact on any group of protected persons. Factors such as a consumer’s debt-to-income ratio and FICO score can be raised as a defense of such claims, but a disparate impact case is expensive to defend and will require dueling statistical experts and analyses of most of a dealer’s portfolio to address discrepancies.
Here’s the bottom line: If credit discrimination is taking place in our industry, it needs to be stopped immediately. Dealership employees have an ethical responsibility to ensure their store is working with consumers on a fair basis. Building that type of ethical and responsible workplace begins with management and the practices it puts in place.
The following are four things you can do to ensure that’s happening:
1. Perform a Self-Test:
The self-test privilege is a program, practice, or study undertaken by a creditor to determine compliance with the ECOA. The self-test protects one from mandatory disclosure in a lawsuit if appropriate corrective action is taken when the results of the self-test show it is more likely than not that there has been a violation of the ECOA or its implementing regulation, Regulation B.
By auditing and analyzing your previous deals on a regular basis, you can justify how your dealership fairly settles on a particular rate and supports fairness to a diverse customer base over time. It can also identify unusual patterns of credit approvals, denials or terms that need to be addressed at your dealership before they become a significant issue. A companywide self-test should be conducted at least once a year.
2. Establish a Common "First Pencil" Benchmark:
You should create standard and fair criteria using factors that are not affected or influenced by protected-person status for starting any deal with a consumer. This is shown by a consistent "first pencil" for all customers before you review their credit. For example, quote a first pencil (e.g., MSRP, term, rate and down payment) that reflects an average or slightly above-average rate for your customer base. Then you can make adjustments based on lender responses to credit applications reflecting the individual customer’s history, credit score and loan-to-value ratio. On rate markups, it is not unlawful to negotiate rates with a customer. However, a consistent deviation in rates by as little as 100 basis points to protected persons has been found to be a disparate impact.
3. Create an Anti-Discrimination Policy and Training:
Develop and enforce a strict, anti-discrimination policy throughout your dealership, and implement a training course or module to support it. Test your employees, monitor their activity, use mystery shoppers and retrain periodically and as necessary.
4. Be Careful With Spot Deals:
Spot deliveries have been scrutinized for credit discrimination on both the initial transaction and the new contract when the spot deal is unwound and re-contracted. Look at your spot deals and see what patterns emerge in relation to women, minorities and other protected persons. This analysis should be part of your self-test.
Implementing these recommendations might not prevent your dealership from being pulled into a CFPB investigation of a lender, but evidence of these practices could significantly help defend your dealership when the new sheriff comes to your town.
Randy Henrick serves as associate general counsel for DealerTrack Inc. E-mail him at randy.henrick@bobit.com.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →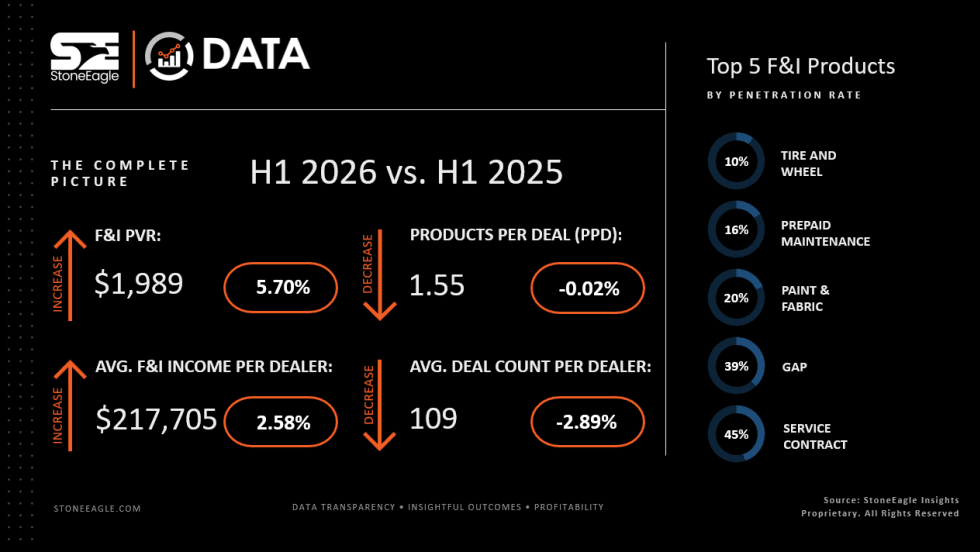
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →