



Hudson: My Job Application to Mr. Trump
In response to rumors that President-elect Donald Trump is preparing to oust the Consumer Financial Protection Bureau's director, the magazine’s legal eagle says he’s the right man for the job.

In response to rumors that President-elect Donald Trump is preparing to oust the Consumer Financial Protection Bureau's director, the magazine’s legal eagle says he’s the right man for the job. Below is the legal insider’s official application for the post. And if you like what you read, go to www.counselorlibrary.com to check out his just-released book, “The Federal Government’s War on Car Dealer.”
***
Dear Mr. Trump
The Washington rumor mill is in overdrive, and one of the tidbits I picked up is there’s a chance you’ll do your “You’re Fired!” routine with Consumer Financial Protection Bureau (CFPB) Director Richard Cordray. If you do, I’d like to throw my hat in the ring for his job.
In the interest of transparency, though, let me first say that I didn’t vote for you. My friend Terry O’Loughlin (director of compliance for Reynolds and Reynolds) did, though, and actually campaigned for you. That should count for something.
But even if I’m not your biggest fan, I think I have the qualifications for the job. What’s more important, I have a plan. You also like “disruptors” as appointment choices. I think my plan qualifies me as a disruptor.
As for job qualifications, I went to law school, and I have practiced consumer financial services law — that’s what the CFPB does, if you haven’t noticed — since 1973. But a lot of folks have professional credentials as good as mine, or better. My chief qualification is that Mary Ed was my Mama.
Mary Ed didn’t have a lot of formal education — just two years at the sort of Alabama “finishing school” that young girls used to attend to learn how to find husbands. But she had uncommonly good common sense. She cast a wary eye at anyone trying to sell her anything, including financial products. I pity the poor “burial insurance” salesmen who went door-to-door all over the South when they ventured up Mary Ed’s driveway to pitch their wares. Mary Ed would disassemble their lousy policies, explain to them what rotten deals they were offering and send them packing.
That is the gist of what I propose for the CFPB. Mary Ed isn’t with us anymore, so I can’t hire her to lead my team of product reviewers, but I’ll find someone with her eye for detail and nose for flim-flam.
“Product reviewers?” you ask.
Well, those are the folks who would implement a plan I recommended long ago, as the CFPB was being proposed. The concern after the 2008 mess, you’ll recall, was that creditors had offered financial products with features like variable rates, prepayment penalties, and “hidden” fees and charges that got consumers in trouble. Those pushing for the establishment of the CFPB argued that we needed a powerful new federal agency to protect consumers from these dangers.
“Phooey,” I said. There’s a much better way to protect consumers. Nothing illustrates that more than how we handle car safety. Every year, thousands of folks are killed on our highways. In order to reduce the carnage, we need safer cars. Do we get safer cars by having the federal government dictate car design and oversee every step in assembly? Nope.
What we do instead is take cars off the assembly line, slam them into immovable barriers and rate how well they stand up to the impact. We then assign a rating to each car and require the car’s manufacturer to post the rating on the car’s window. Want a really safe car? Look for five stars. Want a deathtrap? Buy a car with no stars. The manufacturers with safe products will crow about them. Those whose products are not safe will have a difficult sell.
If we use that system to protect lives, why shouldn’t it work to save consumers’ pocketbooks?
So, I’d pink-slip about 1,400 of the Bureau’s 1,600 employees (about half of them lawyers), keeping the 200 smartest and most experienced ones (20 could probably do the job, but remember, we’re talking about the federal government here). I’d have that group (we’ll call them the “Mary Ed Department”) come up with standards for financial products and services, starting with the most common products, including mortgages, credit cards and auto financing.
The group would create a rating system that financial service providers could use to test their offerings. As an example, a 20% down payment, fully-amortizing first mortgage with a fixed rate, no prepayment penalty and reasonable late charges, grace periods and bounced check fees would earn five stars. A no-down-payment, variable rate balloon mortgage with a teaser rate, packed with gouging late charges and bounced check charges would earn no stars. Armed with the knowledge that one mortgage was safe and the other toxic, consumers would choose the one they wanted.
A few of those 200 folks could also write or amend rules as needed. The current CFPB focuses on enforcement instead of rules, preferring the fuzzy lines and flexibility that enforcement actions provide. Responsible creditors want bright-line rules, so we’ll tell ‘em what’s permitted and what’s not.
I have a couple of other qualifications for the job you might want to consider. I won’t need a big salary because I don’t plan to work very hard. We already have a house in Maryland within commuting distance of the Bureau, so I’ll have no moving expenses. And I like dogs.
So there’s my job application. I can start any time. So c’mon, man, give me a shot. It would make Mary Ed proud.
Tom Hudson is a partner in the law firm of Hudson Cook LLP and one of the industry’s top insiders and the author of several compliance manuals available at CounselorLibrary.com. Copyright CounselorLibrary.com 2015, all rights reserved. Single publication rights only, to F&I and Showroom. (12/16) HC# 4851-0086-7902 v.1.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →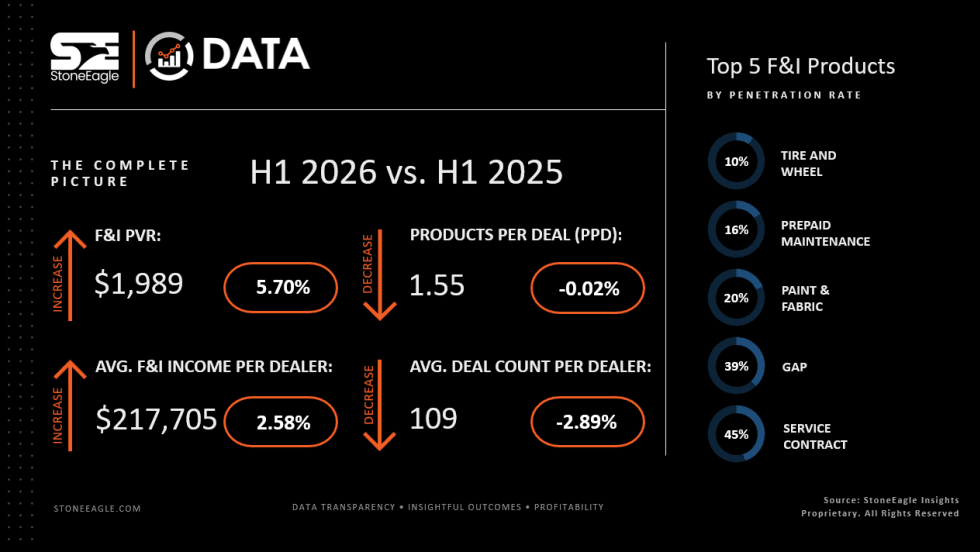
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →