



Rich Cordray’s Legacy and The Future of the CFPB
A former bureau official reflects on her time under former CFPB Director Richard Cordray, and explains why the industry shouldn’t be breathing a sigh of relief with his departure.
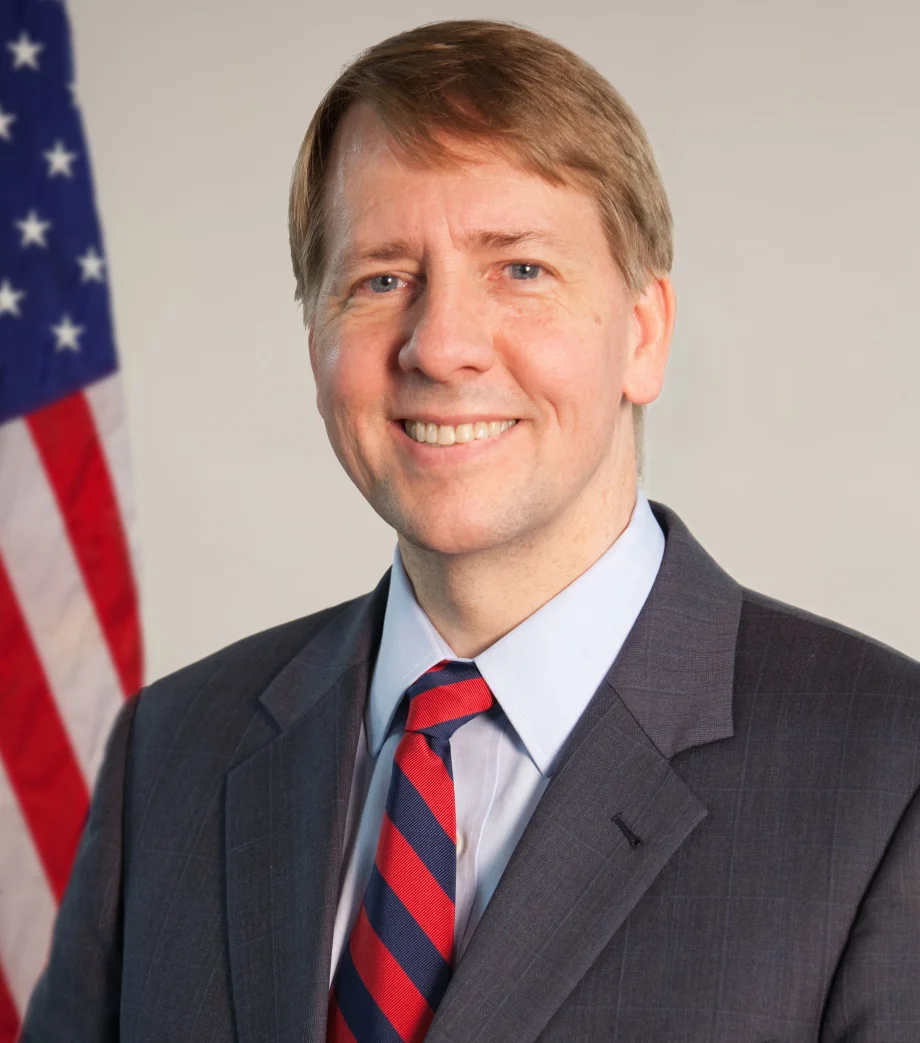
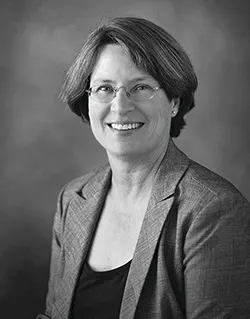
It’s official. Richard Cordray has left the Consumer Financial Protection Bureau (CFPB). He was given a new agency with enormous enforcement authority. And, yes, he wielded that authority forcefully. But there’s more to Rich than the aggressive law enforcer he came to be known as.
See, I worked with Rich to stand up the bureau and as a deputy enforcement director. In the summer of 2014, I decided to leave after four years at the bureau. I wanted to tell Rich immediately and waited until what I thought was a reasonable hour — 10 a.m. ET — to call him. He answered in a whisper: “Lucy, Lucy, how are you?” He then explained in a hush that it was 7 a.m. in California, where he was vacationing with his family. I was embarrassed, but he welcomed my call. I then started to tell him my news, only to lose the connection in mid-sentence.
I tried back, but it happened again, and then again. I stopped trying after four attempts. Then he tried several times to reach me. When I finally delivered my news, the call was lost again. He sent me this text minutes later: “So I know it was not optimal to labor thru NINE calls to convey that message, but you will always be special for having taken the risk to make things work for me and the bureau and I am forever grateful to you. RC.” I kept Rich’s text because it reflects on his character and legacy as the CFPB’s first director. He has been tireless, dogged and committed in his pursuits. And in leading the bureau’s staff, he was supportive, warm and, yes, funny.
So what is Rich’s ultimate legacy as the bureau’s first director? Well, he accomplished many things. He took the reins from Elizabeth Warren, who stood up the bureau initially, and built it up to an agency of 1,600 employees. He completed mortgage rulemakings mandated by Dodd-Frank and discretionary rulemakings, such as the payday rule, in his zeal to protect consumers. He oversaw the first federal agency with supervisory authority over both banks and nonbanks, including first-time examination authority over the national credit bureaus and larger market players in auto finance, debt collection and other industries.
Ultimately, though, Rich’s legacy is that of an aggressive law enforcer who joined and now leaves the agency with a strong enforcement focus.
Before joining the CFPB, Rich served as Ohio’s attorney general. Warren brought him to the bureau to serve as its first enforcement director. When he joined the nascent enforcement team, he jumped into the fray, sprinting to build the enforcement office into a 150-strong team of litigators and investigators. Historically, federal prudential regulators have prioritized their supervisory mission — a confidential, nonpublic process — over public enforcement actions. As the enforcement director, Rich made sure that enforcement shared equal footing with supervision, integrated within the same division. When Rich became the bureau director, he continued to prioritize the agency’s law enforcement mission.
In one of his most controversial moves, he ordered PHH Corp. to pay more than $109 million in disgorgement — about 17 times the hearing officer’s recommendation — and ruled that no statute of limitations applied in the bureau’s administrative forum. Last month, when he announced his intent to leave, his message to the agency’s staff emphasized the $12 billion in consumer relief obtained by the bureau through its enforcement actions.
For better or worse, Rich’s legacy is as an aggressive law enforcer. So, with his exit, should industry breathe a big sigh of relief? While it’s too soon to say, it’s safe to say that the CFPB and its dedicated staff are not going away. It’s a powerful agency with a host of tools, and it will still find a way to do its job to protect consumers.
Under the Trump Administration, this likely means more use of the nonpublic supervisory process and less use of rulemaking. On the enforcement side, I expect the agency to implement procedural protections for companies under investigation, make more efforts to resolve cases short of litigation, and focus its enforcement might on cases akin to fraud.
Bottom line: Administrations come and go, but the CFPB is here to stay. And in the end, the CFPB will look kindly on companies that maintain a strong compliance management system, and maybe not so kindly on companies that don’t.
Lucy Morris is a partner in the Washington, D.C., office of Hudson Cook LLP and former Deputy Enforcement Director at the CFPB. She can be reached at lucy.morris@bobit.com. Nothing in this article is legal advice and should not be taken as such. Please address all legal questions to your counsel.
More Auto Finance

Interest Rates Further Squeeze Auto Consumers
Last month’s hike and a potential second increase this month add to a growing list of inflation woes that could continue to dent overall car sales.
Read More →
Mind Your Process
Consistent steps taken in various aspects of the F&I office can make valuable differences over time, similar to an outline for a best-selling book.
Read More →
Top Five Credit Application Fraud Flags
Compliance audits regularly reveal bad habits that can lead to fraud charges and should have been stamped out decades ago.
Read More →
More Auto Loans for the Taking in August
Riskier categories were on the uptick for the month as lenders loosened access in several areas while balancing out the exposure in another, Cox Automotive reported.
Read More →
July Was Hot for Auto Borrowers
Credit proved readily available for many, but most loans left buyers in negative territory, Cox Automotive said.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Auto Refi Savings Surge
Consumers with 84-month auto loan terms who refinanced saved the most on monthly payments, according to a new report by auto refinancing provider Caribou.
Read More →
Subaru Enters Lending Business
The automaker follows other brands in adding captive financing in the U.S., and says the move will strengthen its position here.
Read More →
Positive Equity Reaches Record High
Mainstream vehicle owners who bought a car seven years ago are likely to have positive equity when trading in for a new vehicle, according to second-quarter Edmunds data.
Read More →
Dealerships Are Paying the Price for Extended Car Loans
Growing negative-equity scenarios mean such lengthy terms should be addressed in a forward-looking way to make them work for the dealer and the consumer down the road.
Read More →