



Special Finance Coming Back Slowly
Leading subprime lending executives joined Jim Bass to discuss how they — and their dealers — are navigating the changing special finance landscape.
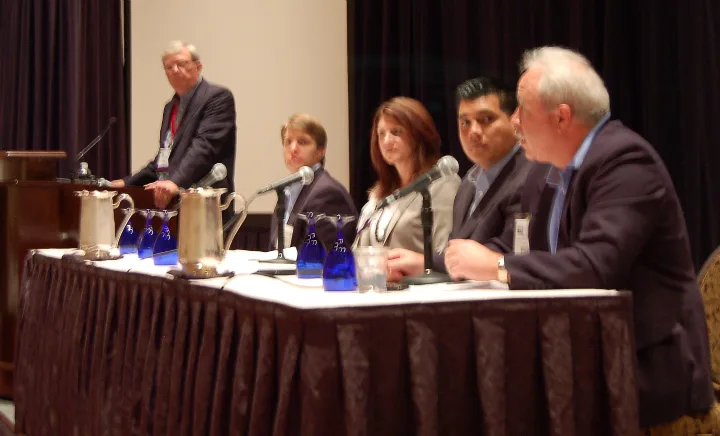
On Tuesday, Sept. 14, at the 2010 F&I Conference and Expo in Las Vegas, Auto One Acceptance Corp. CEO and F&I and Showroom contributor Jim Bass assembled a panel of leading finance executives to discuss the current state of the subprime marketplace.
Bass was joined by Capital One Auto Finance’s Steve Braskamp, Santander Consumer USA’s Deborah Malinowski, Westlake Financial’s Mark Vazquez and Chase Auto Finance’s Paul Rule. Dealers in attendance were treated to a lively discussion that covered a wide range of topics. The magazine caught up with Bass to get his impression of what the panelists said.
F&I: Jim, this isn’t the first time you have led this panel. How did the mood of the execs and attending dealers compare to years past?
Bass: There is no doubt that the attendees are more upbeat than they have been in the last couple of years. There is much more activity in the nonprime and subprime finance arena and there is even some competition among the finance companies to obtain business.
F&I: When did the panelists say they expect subprime to grow again? Is there greater potential in any particular region or among a certain type of dealer or customer?
Bass: Subprime is already growing, due to the increased interest in the securitization market and the willingness of the depositary institutions to purchase more of the subprime paper from dealers. The fact is that subprime pools of finance contracts have performed much better than expected over the last couple of years and this has given the investment community confidence to support this segment of the finance industry. I believe that the franchise market will still be favored, but as competition among the finance companies heats up, independent dealerships also will benefit.
F&I: Dealers have complained that fees for special finance contracts are prohibitively high. From your discussion with the lender executives, do you see that changing?
Bass: I hate to say it, but fees, or discounts on purchases of finance contracts, fluctuate with the cycle of the auto finance business. At the moment, and for the last couple of years, there has been a lack of capacity and that has enabled the finance companies to price their purchase of contracts more in the their favor.
As more capital comes into the market and the desire to maintain or grow market share builds, fees will decrease. However, the risk–based pricing models continue to grow in sophistication and there is a pricing level that will not be penetrated, no matter the competition — except by finance companies that are not cognizant of their true financial position.
F&I: There may always be some disagreement as to the definition of “special finance,” but did the panel offer any insight into which direction the SF needle is moving on the credit spectrum gauge?
Bass: Again, this is a function of the need for yield on the part of the finance companies. Many of the larger players have retreated up the scale to somewhere north of, to use something generally representative, a FICO score of 560. However, there are still several companies, such as Westlake Financial, Credit Acceptance and Friendly Financial, that either do not utilize credit scores at all, or the use is minimal. That allows much lower scoring applicants to purchase a vehicle. Generally, you could expect that the lower the score, the higher the annual percentage rate (limited by state regulations) and the higher the discount or fee charged by the finance company. It’s all about the net yield to the finance company.
F&I: You pointed out that many lenders are still burdened with inaccurate or misleading applications. Do lending executives feel that dealers truly grasp the importance of submitting airtight credit apps and providing the required stips?
Bass: Finance company executives absolutely understand the importance of accurate application data. The problem in the past has been with dealership personnel and customers, in some cases, not being completely factual in the application data being submitted. These problems are often uncovered in the pre-funding interview with the borrower, but not always. Consistent practice of submitting applications with questionable data can, and often does, result in a finance company refusing to do further business with an offending dealership.
F&I: In addition to airtight apps, can you point to one best practice that can elevate a dealer to “favorite” client status?
Bass: Although the panelists claimed to not care about look-to-book ratios, I still think that the dealership comes out ahead when it pays attention to the published guidelines of the finance companies. I believe a dealership becomes more important to the finance company if the number of finance contracts offered to and purchased by the finance company is higher.
F&I: In the weeks before the show commenced, General Motors was working to finalize its acquisition of AmeriCredit Corp. Was there any speculation among the panelists as to how this move will affect AmeriCredit’s buying habits or funding capacity, and what effect, if any, the acquisition will have on the subprime lending landscape?
Bass: This will be very interesting as it develops. AmeriCredit executives have said that they will be able to maintain their way of doing business, signing dealerships and using the securitization markets for funding. However, I find it hard to believe that ownership by GM will not result in preference being shown to GM franchises, to the possible detriment of other dealerships, both franchised and independent.
If AmeriCredit is to rely upon its own resources for funding, there is a finite limit as to just how much funding capacity will be available — that’s what I think will drive AmeriCredit’s approach to the dealership market. Another factor is that it is very unusual in an acquisition that the acquiring company doesn’t force its culture onto the acquired company. So, which group of dealerships will be favored in the long run? Seems obvious to me.
More F&I

AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →