



Utilizing Vehicle History to Minimize Portfolio Risk
Incorporating vehicle history reports into the lending decisions can help uncover hidden issues with the vehicle and adjust loan terms accordingly.
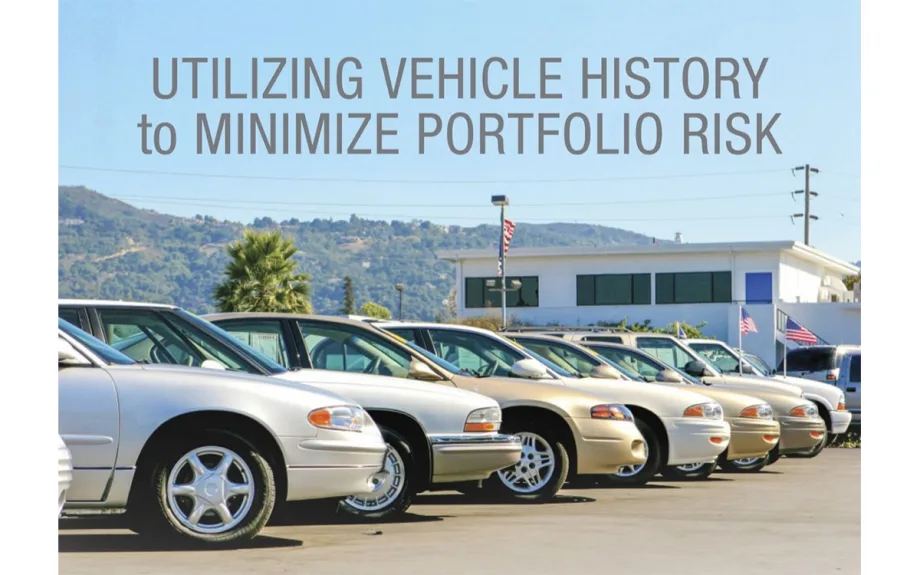
Incorporating vehicle history reports into the lending decisions can help uncover hidden issues with the vehicle and adjust loan terms accordingly.
IMAGE: GettyImages.com
While the automotive industry suffered an immediate impact due to stay-at-home orders and business restrictions during the early stages of COVID-19, it has slowly rebounded over the last several months. Even with the recovery, there’s still economic uncertainty moving forward. Many lenders will look to mitigate portfolio risk while continuing to extend loans to prospective car buyers. To accomplish this, more traditional risk attributes, such as a borrower’s credit score, payment history and utilization rate, will continue to factor into lending decisions. However, during these extraordinary times, lenders should also consider an underutilized tool — vehicle history.
With so much economic uncertainty still lingering, it’s important for lenders to feel confident in the loans they are extending while finding ways to make the loan manageable for consumers.
Often, vehicle history reports are considered a tool for dealers and consumers. But if we drill down into its value proposition — identifying potential hidden defects during the used car buying process — vehicle history reports can benefit lenders as well.
Think about it. A lender’s portfolio risk does not solely rest on the consumer, there’s also inherent risk within the vehicles. For instance, if a vehicle has hidden defects, the owner may have to spend more on maintenance, ultimately hindering their ability to make a monthly payment. Or, if the vehicle is repossessed, unidentified damage that impacts the vehicle’s drivability could hurt a lender’s potential to recoup losses at auction. The more lenders understand about the used vehicles they’re financing, the better positioned they will be to adjust loan terms and mitigate risk exposure.
The Impact of Unidentified Physical Damage
According to Experian’s Q3 2020 Market Trends Review, there are more than 281 million vehicles on the road. And our research indicates approximately four out of 10 of the cars and light-duty trucks on the road have been in at least one accident, and around 20% of all vehicles in operation have been in multiple accidents. That’s a significant volume of vehicles on the road that have been in at least one accident, particularly when considering the universe of used vehicles that could potentially be financed down the line.
Even if a vehicle has been completely reconstructed and repaired, the value of the vehicle still diminishes. A recent Mitchell Industry Trends Physical Damage Report states, in Q2 2019, the average diminished value for a vehicle involved in an accident was $3,151, and the diminished value could be higher depending on the severity of the damage. In other words, if a lender unknowingly finances a vehicle that has been in an accident for $10,000, the actual value of the vehicle may be around $7,000 — a significant discrepancy that could be costly for lenders.
In some cases, lenders rely on intensive expert inspections to evaluate the current condition of an individual vehicle; however, these require significant time and physical access to the vehicle. With business restrictions and social distancing, it isn’t easy to implement the process at scale. Vehicle history reports can make the process more efficient and provide lenders with insight into reported accidents.
The Lending Landscape
The risk associated with financing a used vehicle is more than physical damage. High mileage, older vehicles, numerous owners and excessive usage can make a used vehicle a riskier addition to a lender’s portfolio. But every lender has their own tolerance for risk. Vehicle history will identify and provide details of risk factors which can help lenders make more strategic lending decisions.
For instance, based on a case study by Experian, that surveyed more than seven million loan applications over a three-year period, we found independent dealers had a much higher rate (29.94%) of loan applications for vehicles considered high risk compared to franchise dealers (6.58%). In addition, vehicles associated with loan applications for independent dealers were more likely to experience a negative vehicle history event. Interestingly, minivans had the highest frequency of negative vehicle history events at nearly 55%, while trucks had the lowest at 32.51%.
Extending loans to a wide range of car shoppers is still a priority; however, lenders need to mitigate portfolio risk. While lenders may feel comfortable with the loan applicant, there may be some hidden risk within the vehicle itself. With so much economic uncertainty still lingering, it’s important for lenders to feel confident in the loans they are extending while finding ways to make the loan manageable for consumers. Incorporating vehicle history reports into the lending decisions can help uncover hidden issues with the vehicle and adjust loan terms accordingly.
Kirsten Von Busch is Experian’s senior product manager of AutoCheck.
More Auto Finance
Interest Rates Further Squeeze Auto Consumers
Last month’s hike and a potential second increase this month add to a growing list of inflation woes that could continue to dent overall car sales.
Read More →
Mind Your Process
Consistent steps taken in various aspects of the F&I office can make valuable differences over time, similar to an outline for a best-selling book.
Read More →
Top Five Credit Application Fraud Flags
Compliance audits regularly reveal bad habits that can lead to fraud charges and should have been stamped out decades ago.
Read More →
More Auto Loans for the Taking in August
Riskier categories were on the uptick for the month as lenders loosened access in several areas while balancing out the exposure in another, Cox Automotive reported.
Read More →
July Was Hot for Auto Borrowers
Credit proved readily available for many, but most loans left buyers in negative territory, Cox Automotive said.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Auto Refi Savings Surge
Consumers with 84-month auto loan terms who refinanced saved the most on monthly payments, according to a new report by auto refinancing provider Caribou.
Read More →
Subaru Enters Lending Business
The automaker follows other brands in adding captive financing in the U.S., and says the move will strengthen its position here.
Read More →
Positive Equity Reaches Record High
Mainstream vehicle owners who bought a car seven years ago are likely to have positive equity when trading in for a new vehicle, according to second-quarter Edmunds data.
Read More →
Dealerships Are Paying the Price for Extended Car Loans
Growing negative-equity scenarios mean such lengthy terms should be addressed in a forward-looking way to make them work for the dealer and the consumer down the road.
Read More →