

CFPB to Supervise Credit Reporting Agencies
Finance sources aren’t the only ones being targeted by the new consumer protection bureau, which announced that it will begin overseeing consumer reporting agencies.
WASHINGTON, D.C. — The Consumer Financial Protection Bureau (CFPB) adopted a rule Monday to begin supervising larger consumer reporting agencies, which include what are popularly called credit bureaus or credit reporting companies. This is the first time these companies will be supervised at the federal level.
“Credit reporting is at the heart of our lending systems and enables many of us to get credit, afford a home, or get an education,” said CFPB Director Richard Cordray. “Supervising this market will help ensure that it works properly for consumers, lenders and the wider economy. There is much at stake in making sure it is both fair and effective.”
Although a small number of large businesses dominate the credit reporting market, there are about 400 consumer reporting agencies in the United States. The market includes the largest credit reporting companies that sell comprehensive consumer reports, consumer report resellers, specialty consumer reporting companies that primarily collect and provide specific types of information, and companies that analyze consumer report data.
The Dodd-Frank Wall Street Reform and Consumer Protection Act authorized the CFPB to supervise nonbanks in the residential mortgage, payday and private education lending markets. For other markets providing consumer financial products or services, the CFPB has the authority to supervise nonbank “larger participants” as defined by rule.
Monday’s rule states that the CFPB will, for the first time, supervise consumer reporting agencies that have more than $7 million in annual receipts. The CFPB’s supervisory authority extends to an estimated 30 companies that account for about 94 percent of the market’s annual receipts. Altogether, the three largest credit reporting companies issue more than 3 billion consumer reports a year and maintain files on more than 200 million Americans.
Previously, consumer reporting was subject only to law enforcement authority at the federal level. And authority to write rules under the federal law governing this system was shared among several agencies. Officials with the CFPB said no single federal government agency could adequately see the entire picture of what was happening in these companies. Now, the CFPB will be authorized to supervise the larger consumer reporting agencies as well as write rules and enforce the law as needed.
The CFPB’s approach to supervising credit reporting will be just like its approach to supervising banks and other nonbanks already subject to CFPB supervision, officials said. The companies will be subject to review of compliance systems and procedures, on-site examinations, discussions with relevant personnel, and they will be required to produce relevant reports.
The rule outlining the CFPB’s supervision of this market will take effect on Sept. 30. At that time, the CFPB will begin its first exams. Officials said the CFPB will publish exam procedures that will provide guidance on how it will be conducting its monitoring.
In February, the CFPB issued a proposed rule to supervise the credit reporting and debt collection markets. The CFPB started with those two markets because of their widespread impact on consumers. The public weighed in on the CFPB’s proposals, and today’s rule is a result of that process. The CFPB plans to finalize its “larger participant” rule on debt collection this fall, and plans to propose additional “larger participant” rules in the future.
For more, click here.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →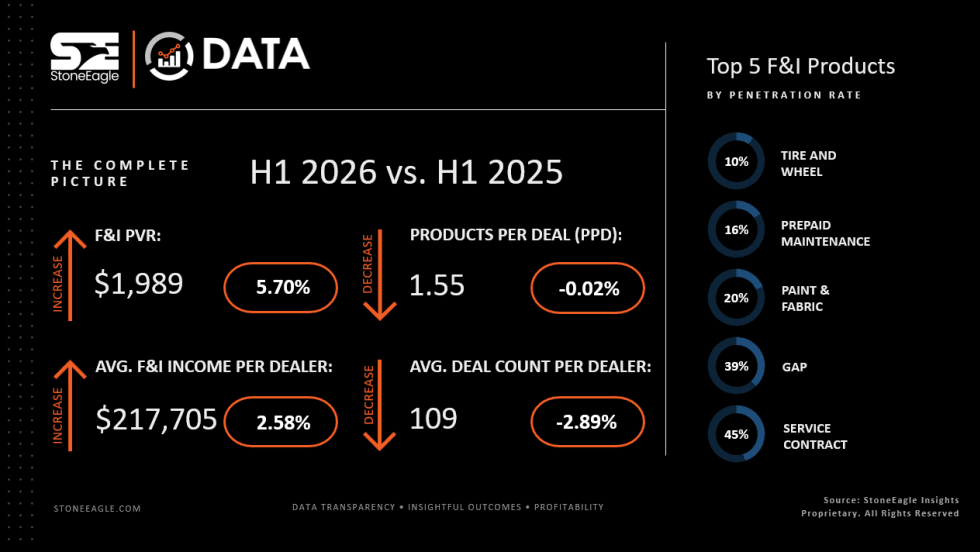
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →