



CUDL: Subprime Pullback Opens Door for Credit Unions
With banks retreating from all risk tiers, an executive with CU Direct Lending said the auto finance market is primed for credit unions to pick up more share. In the first quarter, credit unions grew their share of the market by 4%.
ONTARIO, Calif. — With banks retreating from all risk tiers, the auto finance market is primed for credit unions to increase their share and broaden their risk spectrum. That was executive Michael Cochrum message to credit union during CU Direct (CUDL)’s June 1 webcast to discuss first-quarter finance trends.
"The suggestion has been made that the banks are lowering their volume because they're giving up or they're walking away from subprime," said Cochrum, who serves as the technology firm’s vice president of analytics and advisory services. "It does appear that they are tightening up across all the spectrums, which gives us, again, a good opportunity to take that market share in an area where we are very strong."
Finance sources across the board retreated from the subprime segment, with even credit unions registering a sharp increase in auto loans extended to prime borrowers. The result, however, was narrow margins, which Cochrum suggested could be rectified if credit unions were to delve more downstream into the high-risk tiers.
"I'm not suggesting that every credit union go out and buy deep and do subprime lending," Cochrum said. "What I am saying is that in order for us to get greater margins on our portfolios, especially as interest rates begin to rise, we need to look at broadening our risk spectrum."
Credit unions did, however, grow their share in the first quarter by 4% from a year ago, while banks decreased their share by 5%. Captive finance companies increased their share by 14%, but Cochrum attributed the surge to the segment attempting to keep pace with manufacturer incentives.
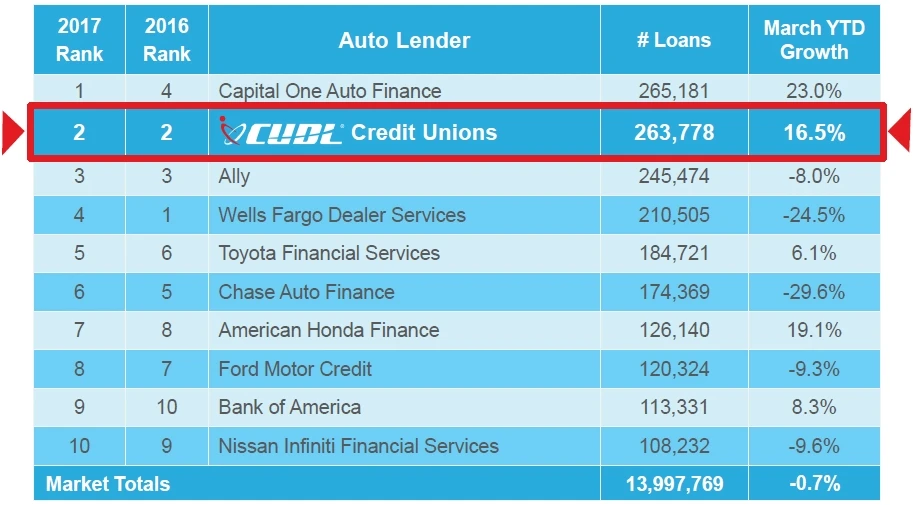
Credit unions on the CUDL platform maintain their No. 2 position on Experian Automotive’s national rankings of auto finance sources, with the segment originating 263,778 auto loans during the period. That was 1,403 more originations than Capital One Auto Finance, which held onto the No. 3 spot during the period.
With the share of leasing growing from 30% at the end of 2016 to 31% in the first quarter, according to Experian Automotive, used-vehicle financing remains a key growth area for credit unions. In the first quarter, used-vehicle financing composed 72% of credit union originations. And that should continue to rise going forward, Cochrum said.
Cash deals, according to Experian Automotive, remained steady at 14% of first-quarter transactions.
Cochrum reiterated his message from the firm’s March 9 webcast — that credit unions can win over more deals and increase their share of the market by improving response and funding times. The executive backed his message by revealing results from an analysis conducted by the technology organization.
According to the analysis, applications that are system approved and never altered resulted in funded deals 93% of the time. The success rate, however, fell to 65% on decisions that were delayed by as little as one to five minutes. Cochrum clarified, however, that he’s not suggesting that credit unions tinker or relax their underwriting guidelines.
“The idea is to simply look at what your underwriters are doing and look for opportunities to turn that manual underwriting into a system decision," he said, adding that system-decisioned applications have risen 16% over the past two years and now compose more than 20% of applications coming through the CUDL platform.
More F&I

AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →