Experian: More Consumers Turning to Leasing, Used Vehicles
With new-vehicle loan amounts and monthly payments rising to record highs during the fourth quarter, leasing’s share of the market grew to record levels. Data from Experian Automotive also showed that more consumers turned to the used-vehicle market in the end-of-year period.
SCHAUMBURG, Ill. — The average amount financed and the average monthly payment for new vehicles financed during 2015’s end-of-year quarter rose to record levels, according to Experian Automotive. But those weren’t the only records set during the period.
The credit reporting agency reported today that the average amount financed for a new vehicle in the fourth quarter increased by $1,170 from the prior-year period to $29,551 — the highest level recorded by Experian. The average monthly payment also rose $11 from a year ago to a new high of $493.
“People shop for vehicles largely based on monthly price, and right now, average dollar amounts for new vehicle loans are soaring,” said Melinda Zabritski, senior director of automotive credit for Experian Automotive. “In order to stay within their budget goals, we have seen that more consumers — even those within the prime and super-prime risk categories — are turning to leasing and used vehicles as cost-effective alternatives to buying new.”
Leasing accounted for a record high 33.6% of all new financing during the quarter, with the average lease payment landing at $412.
Additionally, used-vehicle loans accounted for 62.8 percent of all vehicle financing, with the average amount financed for a used vehicle coming out to $18,850. The average monthly payment for a used vehicle, according to Experian Automotive, was $359, with payment gap between new and used widening to an all-time high of $134 in the fourth quarter.
“Over the course of the last few years, we have seen the market stabilizing nicely,” Zabritski noted. “Credit scores are flattening out for new-vehicle financing and more prime consumers are shifting to used, which is helping increase the average score there as well.”
Experian reported that average credit scores across the board have flattened in the past few years. The average credit score for a new vehicle loan was 711, down from 712 in the prior-year period. Average credit scores for new vehicles peaked at 736 in 2009, then dropped 25 points from that period’s end-of-year quarter to the fourth quarter 2015. However, in the past six years, according to the firm, average credit scores for new-vehicle loans have dropped by only four points each year.
For used vehicles, average credit scores increased by one point to 649. Used-vehicle scores also have been relatively flat in recent years after peaking in 2009 at 657.
Here are other findings from Experian Automotive’s fourth quarter report:
Reliance on financing continues to grow, with 85.9% of all new vehicles and 54.7% of all used vehicles sold during the period having been financed.
The Top 5 models leased were the Honda Civic, Honda Accord, Toyota Camry, Toyota RAV4 and Ford Escape.
The Ford Fusion and the Chevrolet Silverado 1500 showed substantial gains in leasing during the period, rising 22% and 38%, respectively
The average interest rate for a new-vehicle loan was 4.63 percent, while the average interest rate for a used-vehicle loan reached 8.78 percent
Average loan terms for new and used vehicles held steady at 67 months and 63 months, respectively
Longer-term loans (those extending 73 to 84 months) for new vehicles grew by 12 percent to account for 29% of all new vehicles financed during the quarter. The percentage of used-vehicle loans with longer terms rose 10.8% to 16.4%.
More F&I
Managing Expectations
Learn how proactive communication, setting clear expectations, and providing solutions when plans change can strengthen customer trust and improve the overall service experience.
The F&I Manager's Report Card
The best managers take the time and attention to measure the behaviors behind the numbers.
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
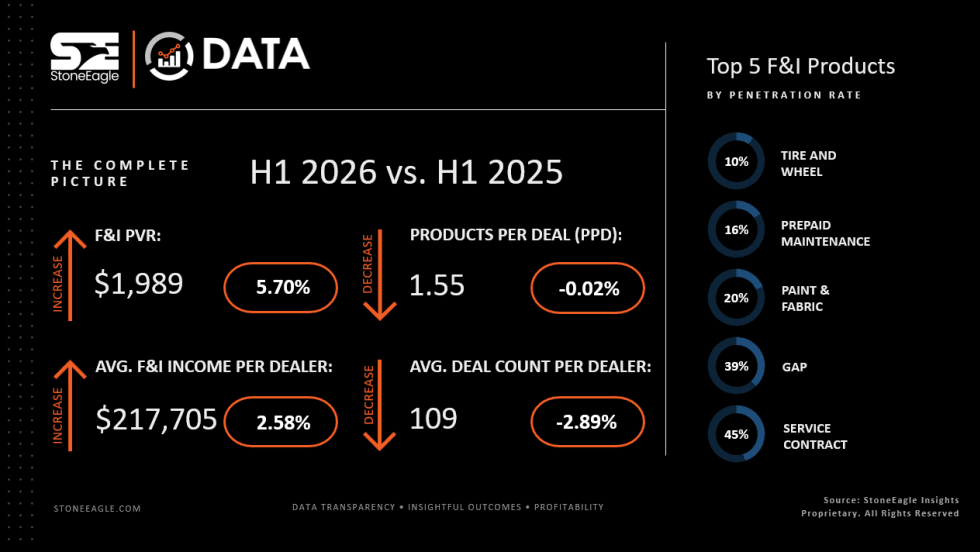
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.