



S&P/Experian: Auto Loan Default Rate Rises in September
Auto was the only loan type to show an increase in its default rate, but officials with the S&P/Experian Consumer Credit Default Indices don’t seem concerned.
NEW YORK —The S&P/Experian Consumer Credit Default Indices showed a drop in default rates for four out of five types through September. The only one to rise was auto.
Default rates for four of the loan types reviewed fell to their lowest level since the 2007-2009 recession. The auto loan default rate, however, rose from 1.09 percent in August to 1.11 percent in September, but the chairman of the index committee for S&P Down Jones Indexes didn’t seem concerned.
"This is still a decent number, as the historic low for [auto] loans was 1.01 percent posted just two months ago in July,” said David M. Blitzer, managing director and chairman of the index committee for S&P Dow Jones Indices.
Bank card, first and second mortgage and composite default rates hit new post-recession lows. Falling from 1.4 percent in August to 1.36 percent in September, the first mortgage default rate has been down or flat for nine consecutive months, another positive housing market statistic. The second mortgage default rate dropped to its lowest level in its eight-year history at 0.64 percent, while the composite index also fell to a post-recession low of 1.46 percent, decreasing from August’s read of 1.5 percent.
“We think it is very fair to say that 2012 has proven to be a period of financial repair for consumers," says Blitzer. "Consumers' financial condition continues to improve as witnessed by these declining credit default rates.
The five cities reviewed by the S&P all showed a decrease in their default rates, with rates in Chicago, New York and Los Angeles falling to post-recession lows. Chicago's rate was 1.82 percent in September, down from 1.92 percent in August. Los Angeles realized its second consecutive monthly decrease, down to 1.45 percent in September from August's 1.6 percent. New York's default rate fell the most., falling 21 basis points from August’s reading to 1.28 percent.
Dallas and Miami also realized major drops in their default rates. Dallas' September rate was 1.03 percent, down four basis points from August. Miami's rate fell by 14 basis points to 2.48 percent in September. It wasn’t a new low, but the rate is down considerably from the 18.89 percent rate witnessed in May 2009.
"There is no doubt that, from a borrowing perspective, the consumer is in a much better place than two or three years ago,” the company wrote in a press release. “We have seen broad-based declining trends in default rates through all of 2012, and all markets and loan types are at or near pre-recession lows. For some of these markets, such as Miami, the difference in the past three years has been quite extraordinary."
The table below summarizes the September 2012 results for the S&P/Experian Credit Default Indices. These data are not seasonally adjusted and are not subject to revision.
S&P/Experian Consumer Credit Default Indices | ||||||||
National Indices | ||||||||
Index | September 2012 Index Level | August 2012 Index Level | September 2011 Index Level | |||||
Composite | 1.46 | 1.50 | 2.10 | |||||
First Mortgage | 1.36 | 1.40 | 1.99 | |||||
Second Mortgage | 0.64 | 0.72 | 1.32 | |||||
Bank Card | 3.70 | 3.77 | 5.36 | |||||
Auto Loans | 1.11 | 1.09 | 1.29 | |||||
Source: S&P/Experian Consumer Credit Default Indices | ||||||||
Data through September 2012 | ||||||||
The table below provides the S&P/Experian Consumer Default Composite Indices for the five MSAs:
Metropolitan Statistical Area | September 2012 Index Level | August 2012 Index Level | September 2011 Index Level | |
New York | 1.28 | 1.49 | 2.01 | |
Chicago | 1.82 | 1.92 | 2.47 | |
Dallas | 1.03 | 1.07 | 1.33 | |
Los Angeles | 1.45 | 1.60 | 2.12 | |
Miami | 2.48 | 2.62 | 4.59 | |
Source: S&P/Experian Consumer Credit Default Indices | ||||
Data through September 2012 | ||||
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →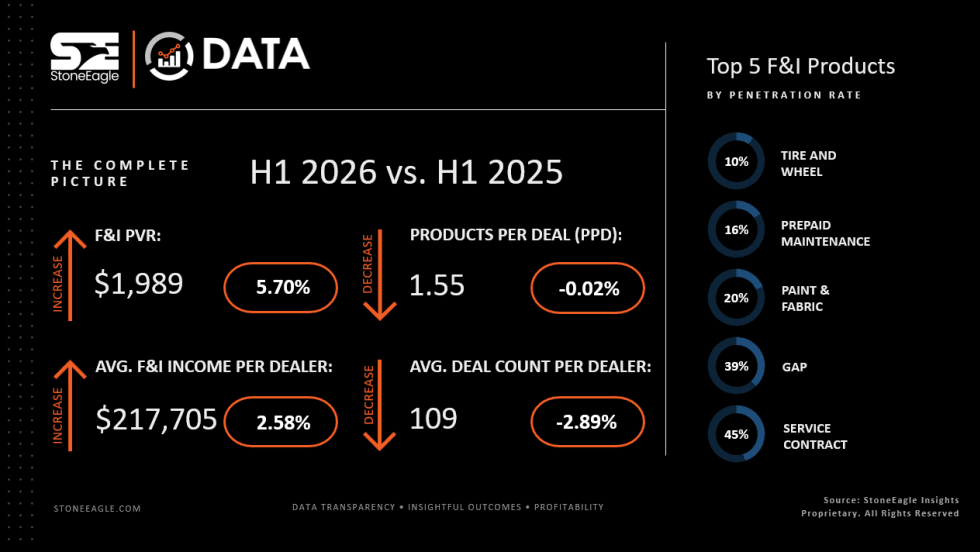
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →