

S&P/Experian: Increase in Default Rates ‘Gives Little Reason for Concern’
The bank card default rate showed the only decrease in August, falling six basis points from July to 2.86%. Auto loan defaults rose eight basis points to 1.01%, but an official with the S&P Dow Jones Indices said the ‘overall credit picture gives little reason to be concerned about default rates.’
NEW YORK — The S&P/Experian Consumer Credit Default Indices showed slight increases in numerous default rates in August, with the composite rate increasing two basis points from July to 0.85%. But officials said the small monthly movements in consumer credit default are no cause for concern.
According to the two firms, August auto loan defaults increased eight points from July to 1.01%, while the first mortgage default rate increased two basis points to 0.68%. The bank card default rate was the only segment showing a decrease in August, falling six basis points from July to 2.86%.
“Despite small monthly movements in consumer credit defaults, the overall default rates are stable and close to the lowest levels since shortly before the financial crisis,” said David M. Blitzer, managing director and chairman of the index committee at S&P Dow Jones Indices. “Bank car default rates are more volatile and slightly higher than those tracking mortgages or auto loans.”
Blitzer noted that compared to a year a year earlier, auto and bank card defaults rose 11 and 15 basis points, respectively, while mortgage loan defaults are 16 basis points lower. “The overall consumer credit picture gives little reason to be concerned about default rates,” he added.
The five major cities reported mixed results in August, with three cities showing higher default rates. New York’s default rate rose 14 basis point from July to 0.91%, while Dallas’ default rate increased five basis points to 0.74%. Chicago’s default rate increased four basis points to 0.93%, while Los Angeles’ default rate decreased three basis points to 0.60%. Miami also reported a decrease — the city’s first since February — with its default rate falling 16 basis points to 1.21%.
“Related data published by the Federal Reserve show that the growth in consumer and household debt is currently about 4.4% per year, increasing about two percentage points faster than nominal GDP growth,” Blitzer continued. “Consumer credit — bank cards and auto loans — grew before, during and after the recent recession and is currently at an all-time high. Mortgage debt peaked in the first quarter of 2008 and reached its most recent low point in the first quarter of 2015. It is now up 2.1% from the low.
“Barring a repeat of the recent and severe recession, both consumer credit and mortgage debt outstanding are expected to continue growing at, or faster than, the pace of nominal GDP growth.”
More F&I
Managing Expectations
Learn how proactive communication, setting clear expectations, and providing solutions when plans change can strengthen customer trust and improve the overall service experience.
Read More →
The F&I Manager's Report Card
The best managers take the time and attention to measure the behaviors behind the numbers.
Read More →
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →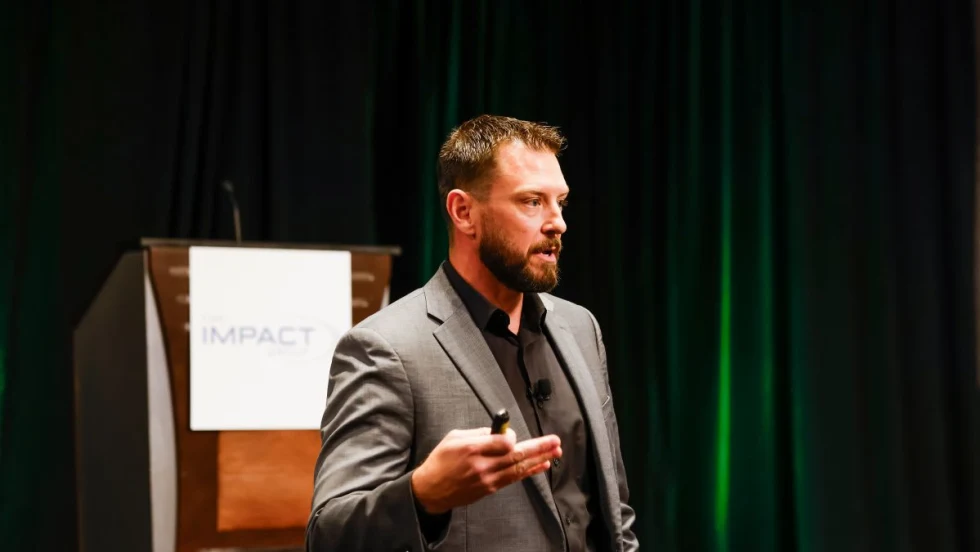
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →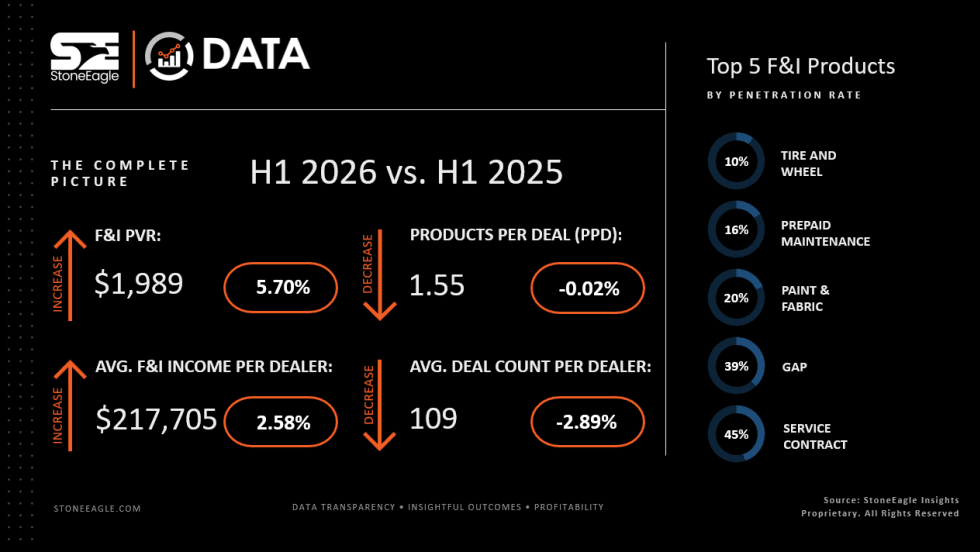
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →