



Wolters Kluwer Offers Risk-Based Pricing Solution
Wolters Kluwer Financial Services is offering dealers, lenders and F&I service providers a number of solutions to help them comply with the new federal Risk-Based Pricing Rule.
BATON ROUGE, La. — Wolters Kluwer Financial Services is offering dealers, lenders and F&I service providers a number of solutions to help them comply with the new federal Risk-Based Pricing Rule.
As of Jan. 1, 2011, automotive dealers, lenders and third-party service providers must notify consumers when they receive materially less favorable credit terms than others based on consumer report information.
The Federal Reserve Board and Federal Trade Commission issued the risk-based pricing rule to complement the existing adverse action notice provisions of the Fair Credit Reporting Act, which requires creditors to notify consumers only if they have been denied credit based on information in their credit report. Under the new rule, dealers, lenders and service providers must provide consumers who will receive less favorable credit terms a risk-based pricing notice before they sign a credit agreement.
The exception to the risk-based pricing rule allows dealers and lenders to provide a credit score disclosure notice to all customers who apply for credit. The exception notice must include the consumer’s credit score, the date it was created, its source, and information about the range of scores and how lenders use them.
Wolters Kluwer Financial Services has several offerings and products designed to assist dealers, lenders and third-party F&I service providers with implementation of the rule, including:
AppOne– Wolters Kluwer Financial Services provides exception credit score disclosure forms free of charge to dealers, lenders and third party F&I service providers using its AppOne platform, which automates indirect lending, credit approval and compliance processes for independent auto dealers and the lenders they work with.
When the dealer accesses and retrieves credit reports via AppOne, the system will automatically enter information into the form about credit scores, ranges and distribution. AppOne will also support custom versions of the credit score disclosure notice furnished by the lender.
Risk-based Pricing Toolkit– The new toolkit features a Pricing Disclosures Guide for Dealers. The guide gives detailed information about when a risk-based pricing notice is required, and how and when the risk-based pricing notice must be provided. It also includes information about the exception credit score disclosure and conditions for using alternative forms.
The toolkit, which is available to dealers and lenders, also provides samples of the exception disclosure and samples of the required disclosure when no score is returned by a credit reporting company. The toolkit features best practices and tips for reducing the risk of non-compliance with the risk-based pricing rule.
Risk-based Pricing Notice Forms – These documents are available in print or electronic format to lenders and third-party service providers.
“Our compliance solutions provide dealers, lenders and service providers with resources to help them quickly and easily meet the requirements of the new rule,” said Lee Domingue, CEO of indirect lending at Wolters Kluwer Financial Services. “These latest offerings showcase Wolters Kluwer Financial Services’ commitment to helping our indirect lending customers improve their compliance programs and increase their efficiency.”
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →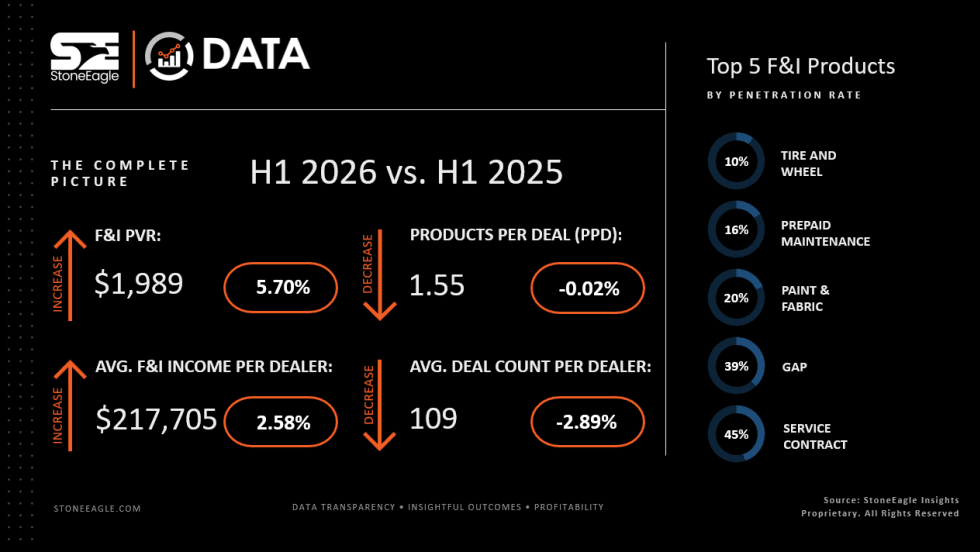
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →