



Part 8: Secure the Funding
It's a terrible feeling when you've put great effort into a deal only to see it go splat because you can't get the customer's loan approved. Don't let this happen to you.

It's a terrible feeling when you've put great effort into a deal only to see it go splat because you can't get the customer's loan approved. Don't let this happen to you.
A deal is only as good as the ability to secure the funding. When loan packages reach lenders after the approval period has expired or arrive with missing documentation, the dealership loses cash flow and sometimes even the loan approval!
Lenders enter into dealership agreements on good faith, relying on the dealership to accurately represent the customer, the deal structure and the vehicle.
The best way to ensure that your deals are funded is to use the lender's guidelines, get the details right the first time and follow the documents all the way to the deposit into the dealership's bank account.
Credit the Source
Lenders can access all three major credit bureaus. They will run the bureau that is most prevalent in the customer's area. For example, a lender will most likely pull a TransUnion bureau for a Texas customer, while the same lender may pull an Experian credit bureau for a customer residing on the West Coast. When the finance representative looks at the same bureau information, it not only makes the credit interview easier, it also prepares the representative to answer the lender's questions about the customer's past credit difficulties.
I am frequently asked if the dealership has the right to show the customer the credit bureau. My answer is no. The practice of showing the credit bureau violates the dealership's subscriber agreement with the credit bureau, which stipulates that the dealership has the right to share only the information the dealership can enter into the credit bureau system: name, address and social security number. It would be wise for you to verify your subscriber agreements with your dealership's legal counsel.
Give Credit Where Credit Is Due
The best way to begin a credit interview is to put your customer in a non-
confrontational environment. Introduce yourself as the one in the dealership who works with lenders to secure loan approvals. Ask for permission to discuss past credit items. Then you can safely say, "During my preliminary credit review, I noticed some credit difficulties (or glitches, hiccups, challenges — choose the word you think the customer will be most comfortable with). What happened during this time period?" Take notes, but don't show the credit bureau to the customer.
When you review credit information with the customer, ask for a recent pay stub to verify stated employment income. When the credit FICO score is low, lenders almost always want verification of income.
Verify the length of residency. Have they been in their house for two or more years? What was their previous address?
Are references listed on the credit application? A lender wants to know where the customer can go when times are tough. Where can the lender find the vehicle?
Document the Deal
The lender's guidelines are the F&I department's best friend. A properly structured deal will get approved much faster than one that seeks an exception to the guidelines.
Use a loan document checklist, and check it twice. Documentation is the key to securing rapid funding. Most lenders will provide a list for you.
Pull the deal apart and separate the loan documentation from the accounting office package. Make it easy for the accounting office to pull the funding package to verify the invoice and add on items to obtain the loan assignment.
Track the loan package. Whether it goes UPS, FedEx, Airborne, messenger, U.S. mail or by e-contract, the funding will most likely return the same way you sent the loan package. Perhaps your dealership can simply fax loan documents to the lender, followed by automatic deposit funding. Regardless of the delivery method, you must track the loan documents to their destination and the funding into the dealership.
Make It a Happy Ending
Again, a deal is only as good as the ability to secure the funding. And secured funding is verifiable; this will be our subject in Part 9.
Jan Kelly is the president of Kelly Enterprises. She is a sales trainer and consultant, convention speaker and frequent contributor to industry publications. For information about training opportunities call (800) 336-4275 or visit her Web site, www.JLKelly.com.
More F&I
AI: Facilitator, Not Fixer, in F&I
The dealerships that thrive in the years ahead will be those that embrace technology while continuing to invest in the people who make customer interactions count.
Read More →
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →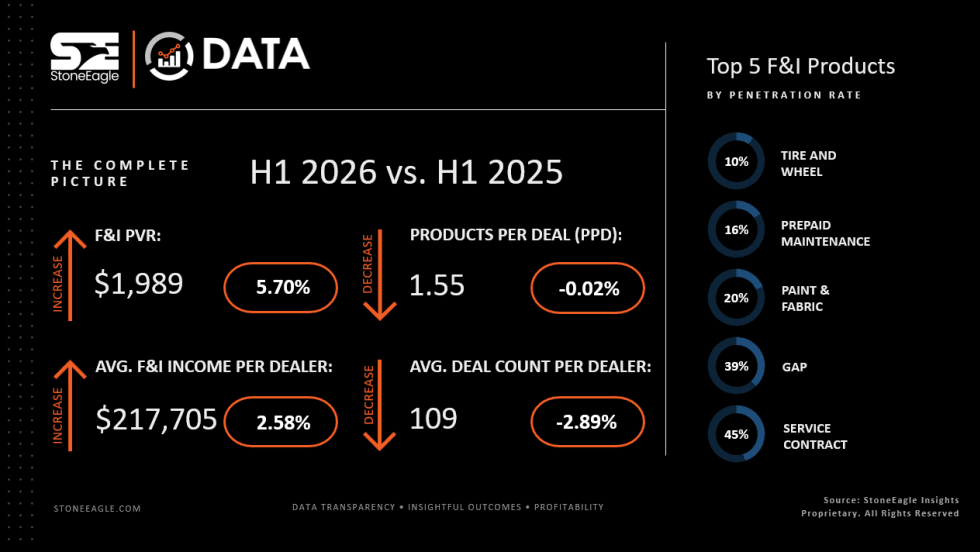
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →