

CU Direct Network Grows Origination Volume 16.4% Through Q2
CU Direct's credit union network was the No. 3 auto loan originator in the first quarter. However, the network posted the highest year-over-year growth in auto originations.
ONTARIO, Calif. — Credit unions accounted for 25% of all auto originations, with the segment capturing $36.8 billion of the $147 billion in total originations during the first quarter of 2016, according to CU Direct’s State of the Credit Union Auto Lending Market report.
In the past few years, auto loans have become a larger part of credit union balance sheets, the firm reported. As of the first quarter of the year, auto loans comprise about 33.7% of credit unions’ total outstanding loans.
“As of Q1 2016, credit unions have about $272 billion in auto loans outstanding; this is about a $34 billion increase versus the Q1 2015 outstanding balance, which was about $240 billion,” said Jose Torres, research analyst for CU Direct.
“Credit union auto origination continues to increase … Q2 and Q3 of 2015 were the height of auto originations, but going forward I believe that it’s not going to be at that high level, but it’s going to continue to grow quite modestly.”
Collectively, credit unions on the CU Direct platform maintained their position as the third largest auto loan originator. However, the group realized the highest year-over-year growth out of all other finance source segments.
“We are still the third largest lender collectively. [We had] a 16.4% year-over-year increase in terms of the number of loans by CU Direct credit unions. [The other banks] are far below what the credit unions are doing on a year-to-year basis. The captives … are actually having some declines or really minimal growth,” Torres said.
Wells Fargo Dealer Services and Ally, which held the first- and second-place positions, posted a 5.2% improvement in orignations and a 6.6% decline, respectively. Posting the largest declines in originations from a year ago were Santander Consumer Finance (down 19.3%), Ford Motor Credit (down 17.1%), and Nissan Infiniti Financial Services (down 16.8%).
An emphasis on leasing was the reason for the declines among captives, Torres noted. In the six months ending in June, 54.9% of all new-vehicle sales were financed and 31.5% were leased. Since banks and credit unions largely deal with financing, they’re able to benefit more from the current market, Torres added.
He added that things could change if leasing continues to steal share from retail financing. Back in 2011, financing held an even larger share over leasing — 62% vs. 18.8%. The split is now 54.9% financed and 31.5% leased, and Torres said he expects that split to lean more toward leasing in the quarters to come.
“In the near future, we may have what the United Kingdom actually experienced, where about 75% of the new cars are actually being leased. Right now we’re at 32%. That’s a long way from 75%, but the trend is moving more and more toward buyers actually leasing cars than financing them,” Torres said.
Both new- and used-vehicle sales are up year to date, according to the report. The demand for trucks remained strong through the first six months of the year. For every car sold, according to the report, 1.5 trucks were sold. New vehicle sales are up about 1.4% from a year ago, while used sales were up 4.8%. While increases bode well for credit unions, it’s the growth in the used segment that will provide the biggest boost for credit unions.
According to the report, 54.8% of current credit union members buy used, while 27.3% buy new.“Used car sales are up a really healthy 4.8% year to date, to 19.1 million, compared to the same time a year ago. For CU Direct Credit Unions, this bodes pretty well as seven out of 10 cars actually finance on the used-car side. For credit unions the used-car side represents a positive, as they are financing more with those cars,” Torres said.
The average term length for consumers financing through credit unions is also on the rise, Torres noted. While the average term length for new cars remained flat from a year ago at 74 months, the average term for used cars rose one month to 68 months.
Interest rates for prime (680+) credit union borrowers are also on the rise. In June, the average interest rate for prime borrowers at credit unions was 3.78%, up from a year ago's 3.36% rate. Interest rates for nonprime (620-679), subprime (550-619) and deep subprime (<550) were either flat or declining.
Interest rates for prime borrowers in the used-vehicle segment were also up. In June, the average used-vehicle interest rate for credit union members was 3.77%, up from 2.66% in the prior-year period. In this segment, however, nonprime and subprime interest rates are on the decline, while deep subprime interest rates are on the rise.
Additionally, credit union delinquencies remain the lowest in the auto finance arena. In the first quarter, 60-day delinquencies represented 0.30% of all loans, compared to 0.29% in the first quarter of 2015.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →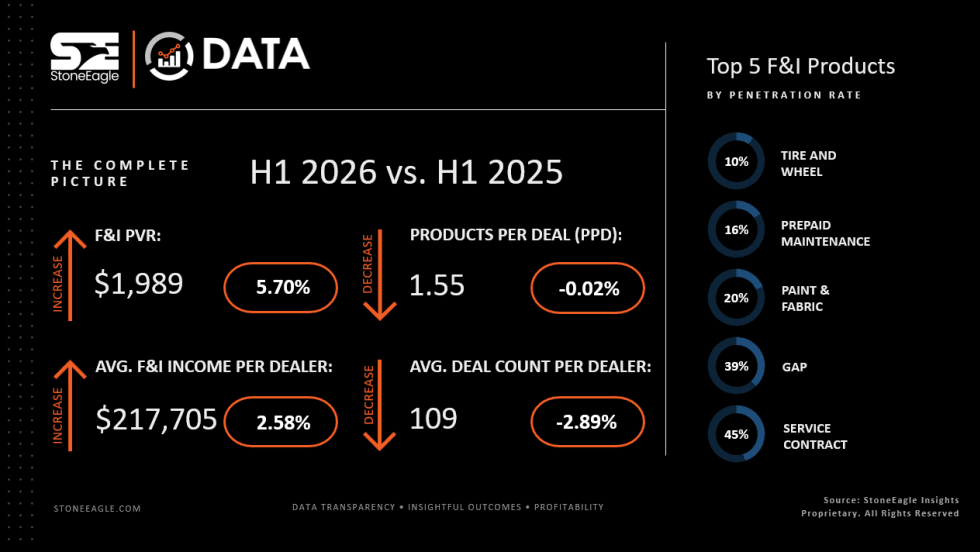
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →