

Delinquencies Up in Q2, the ABA Reports
The American Bankers Association found that delinquencies across all credit segments rose six basis points in the second quarter. Overall, delinquencies remain significantly below their 15-year average.
WASHINGTON — Consumer delinquencies rose slightly across most loan categories in the second quarter, according to the American Bankers Association (ABA). The trade group, however, noted that delinquencies remain significantly below their 15-year average.
The association’s composite ratio, which tracks delinquencies in eight closed-end installment loan categories, rose six basis points to 1.76 percent of all accounts in the second quarter. Despite this increase, the ratio is still 25 percent below the 15-year average of 2.36 percent.
Bank card delinquencies remained virtually unchanged, according to the ABA — rising one basis point to 2.42 percent of all accounts in the second quarter, 37 percent below their 15-year average of 3.85 percent.
James Chessen, the ABA’s chief economist, attributed the slight uptick in delinquencies to a sluggish economy and a limit to how much consumers can improve their financial positions.
“A leveling off in delinquency rates was inevitable after a four-year downward trend that saw consumers reduce debt and dramatically improve their personal balance sheets,” Chessen said. “The good news is that delinquency rates remain near historical lows and are unlikely to spike in the near future.”
The second quarter 2013 composite ratio is made up of the following eight closed-end loans (All figures are seasonally adjusted based upon the number of accounts):
Closed-End Loans
Personal loan delinquencies rose from 1.82 percent to 1.94 percent.
Direct auto loan delinquencies fell from 0.91 percent to 0.88 percent.
Indirect auto loan delinquencies rose from 1.66 percent to 1.72 percent.
Mobile home delinquencies rose from 3.92 percent to 3.96 percent.
RV loan delinquencies held steady at 1.20 percent.
Marine loan delinquencies rose from 1.50 percent to 1.55 percent.
Property improvement loan delinquencies rose from 0.74 percent to 0.80 percent.
Home equity loan delinquencies rose from 3.72 percent to 3.83 percent.
In addition, ABA tracks three open-end loan categories:
Open-End Loans
Bank card delinquencies rose from 2.41 percent to 2.42 percent
Home equity lines of credit delinquencies fell from 1.91 percent to 1.90 percent.
Non-card revolving loan delinquencies rose from 1.19 percent to 1.58 percent.
More F&I
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →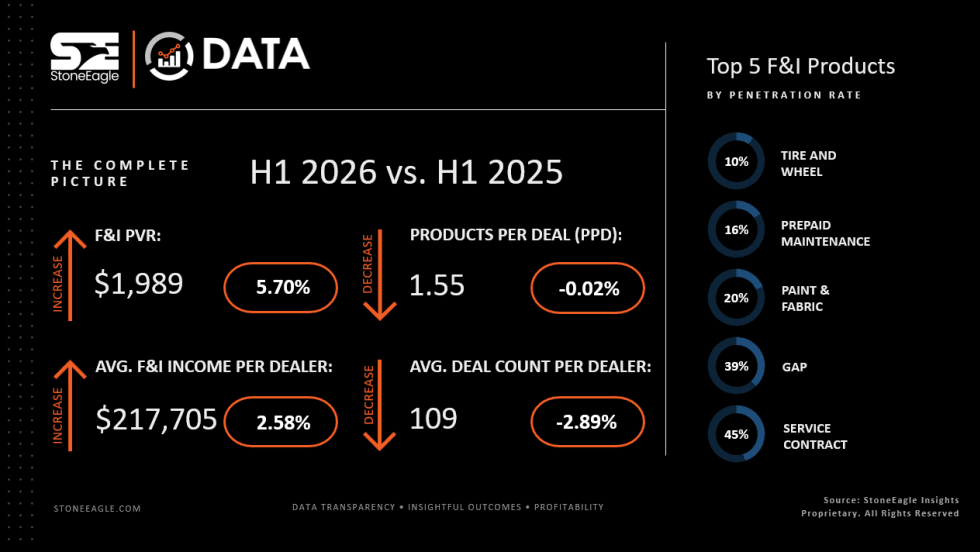
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Leading with Purpose
In this video, Trent White explains how understanding your people’s 'why' is a key leadership responsibility of F&I professionals and how that mindset drives dealership engagement, trust and performance.
Read More →
Integrating Nontraditional F&I Products
The niche presents a strategic advantage for auto dealerships as they move to adapt to fast-changing consumer expectations in today’s market.
Read More →