



Fitch: Stress Tests Not Able to Dent U.S. Prime Auto Loan ABS
Fitch said a majority of 'AAAsf' rated U.S. Prime Auto Loan ABS would be able to withstand a recession and serious declines in used-vehicle values.
NEW YORK — The majority of 'AAAsf' rated U.S. Prime Auto Loan ABS outstanding classes of notes are comfortably able to withstand a hypothetical recession and material declines in used-vehicle recovery rates, according to recent stress tests conducted by Fitch Ratings.
Under the moderate scenario, Fitch would expect all 'AAAsf' rated notes to likely remain rated investment grade (IG), with nearly three-quarters of these ratings expected to remain rated 'AAAsf,’ while nearly 90 percent would stay in the top two rating categories.
Fitch believes the likelihood of the severe scenario (unemployment rising to 20 percent and recovery rates dropping to 25 percent) occurring is extremely remote. However, if this were to occur, Fitch's analysis found that the scenario would likely cause 67 percent of outstanding 'AAAsf' rated notes to be downgraded to non-investment grade (NIG), while the remaining 33 percent would be expected to remain rated IG.
Fitch subjected its ratings on prime auto loan ABS to two stress scenarios, moderate and severe, by stressing the two factors that most directly affect asset performance, U.S. unemployment and recovery rates on used-vehicle values of defaulted and repossessed loans.
The moderate scenario mimics conditions observed in the United States during the recessionary 2008-2009 period. Fitch calibrated the severe stress scenario to be substantially more stressful, assuming unemployment would grow above peak levels. It also assume wholesale vehicle values would fall below historical lows experienced during the 2008-2009 period.
To gauge the impact on outstanding 'AAAsf' ratings, Fitch stressed unemployment from a base level of 6 percent to 12 percent under the moderate scenario, and 20 percent for the severe case. Fitch reduced assumed wholesale vehicle values from an historical average of 50 percent down to 40 percent under the moderate case and 25 percent for the severe case.
According to results, seasoned transactions (2006-2008 vintages) which are producing some of the highest loss rates to date could withstand even the severe stress since they are largely paid off, and have built significant enhancement.
Transactions originated during the 2009-2012 period, which are producing some of the lowest loss rates to date, are more susceptible to downgrades under the severe scenario, but mostly will be able to withstand even this stress. Under the moderate scenario, most 'AAAsf' ratings issued during this period would remain 'AAAsf' and no ratings would be expected to drop below IG.
The moderate scenario was designed to be consistent with what was observed during the 2008-2009 period. The severe scenario assumed a dramatic downturn in the U.S. economy, with unemployment rising to 20 percent and vehicle values declining to levels never seen before.
Of note, the rating migration under the moderate scenario is much more severe comparable to the actual rating migration experienced during 2008-2009. During this period, Fitch only issued three downgrades on IG-rated prime auto loan ABS notes. Further, virtually every subordinate note issued and rated by Fitch experienced positive ratings actions, including those from the 2006-2009 vintage transactions.
The stress tests were carried out as part of a wider study on how robust global structured finance ratings are to a prolonged economic downturn. Fitch expects to conduct similar stress test reports in the coming months for other structured finance asset classes.
The “US Prime Auto Loan ABS Stress Test” is available here.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →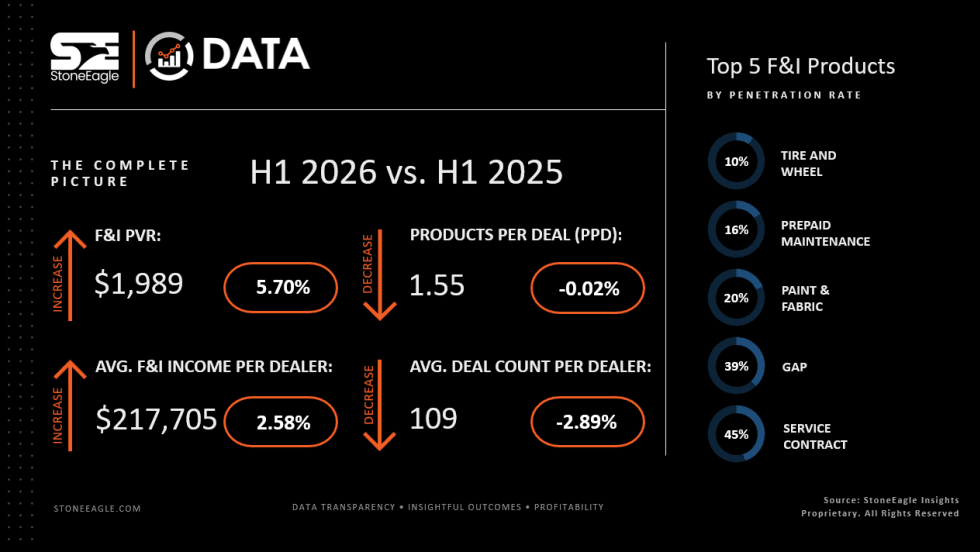
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →