



GM Financial Realizes Profit Increase, Ally Slowed by ResCap
GM Financial reports second-quarter profit gains, while Ally Financial’s profitable auto-lending segment is weighed down by the company’s mortgage business.
Ally Financial’s auto lending business did post a profit, but the former captive’s mortgage subsidiaries continued drive up losses. Ford Credit and GM Financial second-quarter performances were better, with the latter reporting solid profit gains.
Ally Financial realized a net loss of $898 million and a core pre-tax loss of $753 million in the second quarter of 2012 amidst its Residential Capital LLC (ResCap) bankruptcy case, which continues to move forward. Ally’s losses are largely a result of the ResCap and various subsidiaries filing for Chapter 11 bankruptcy.
"The second quarter of 2012 marked a seminal moment for Ally. Strategic actions were announced in May that aim to permanently address the legacy mortgage risks and put Ally on an accelerated path to repay the remaining U.S. Treasury investment," said Ally CEO Michael A. Carpenter. "The ResCap Chapter 11 case continues to move forward, and plans to pursue alternatives for Ally's international operations are underway. Successful completion of these activities will enhance Ally's capital position and further clarify our mission to be the leading value-added auto finance provider to U.S. dealers, supported by a growing direct bank with a distinctive, customer-friendly approach."
The company’ core auto-lending segment did post a profit, however, of $746 million, up from $700 million a year ago and $611 million in the first quarter.
Ford Motor Credit Co. reported a net income of $296 million in the second quarter, compared to $383 million the year prior. On a pre-tax basis, Ford Credit earned $438 million in the second quarter, compared with $604 million in the previous year.
"We had another solid quarter, led by our ongoing strong credit-loss performance," Chairman and CEO Mike Bannister said. "We are on track to achieve our projected full year pre-tax profit. Our business plan is working, delivering profits and distributions for Ford, and support of Ford vehicle sales around the world."
As the second quarter concluded, Ford Credit's net receivables totaled $84 billion, compared with $83 billion at the end of 2011. Managed receivables were $86 billion in the second quarter, up from $85 billion on Dec. 31, 2011.
On the last day of the second quarter, managed leverage was at 8.1 to 1, compared with 8.3 to 1 at the close of fourth quarter 2011. Ford Credit distributed $100 million to its parent in the second quarter.
Despite its competitors’ losses, GM Financial managed to record a profit in the second quarter. The company announced net income of $136 million for the quarter ended June 30, 2012, compared to $96 million for the same quarter of 2011. Net income for the first half of the year was up to $249 million vs. $173 million in 2011’s first half.
According to GM Financial, loan originations were $1.5 billion for the quarter ended June 30, 2012, compared to $1.4 billion for the quarter ended March 31, 2011, and $1.3 billion for the quarter ended June 30, 2011. Loan originations for the six months ended June 30 were $2.9 billion, compared to $2.5 billion for the six months ended June 30, 2011. The outstanding balance of consumer finance receivables totaled $10.4 billion at June 30, 2012.
Lease originations for General Motors vehicles were $394 million for the second quarter vs. $384 million in the first quarter and $173 million for the second quarter last year. Lease originations for the six months ended June 30, 2012, were $778 million, compared to $484 million for the six months ended June 30, 2011. Leased vehicles, net, totaled $1.4 billion at June 30, 2012.
Consumer finance receivables 31-to-60 days delinquent were 4.1 percent of the portfolio at June 30, 2012, compared to 4.4 percent at June 30, 2011. Accounts more than 60 days delinquent were 1.5 percent of the portfolio at June 30, 2012, compared to 1.7 percent a year ago.
Annualized net credit losses were 1.5 percent of average consumer finance receivables for the quarter ended June 30, 2012, compared to 2.4 percent for the quarter ended June 30, 2011. For the six months ended June 30, 2012, annualized consumer net credit losses were 2.0 percent, compared to 3.2 percent last year.
GM Financial had total available liquidity of $2.1 billion at the end of the second quarter, consisting of $952 million of unrestricted cash, approximately $891 million of borrowing capacity on unpledged eligible assets and $300 million on a line of credit from GM.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →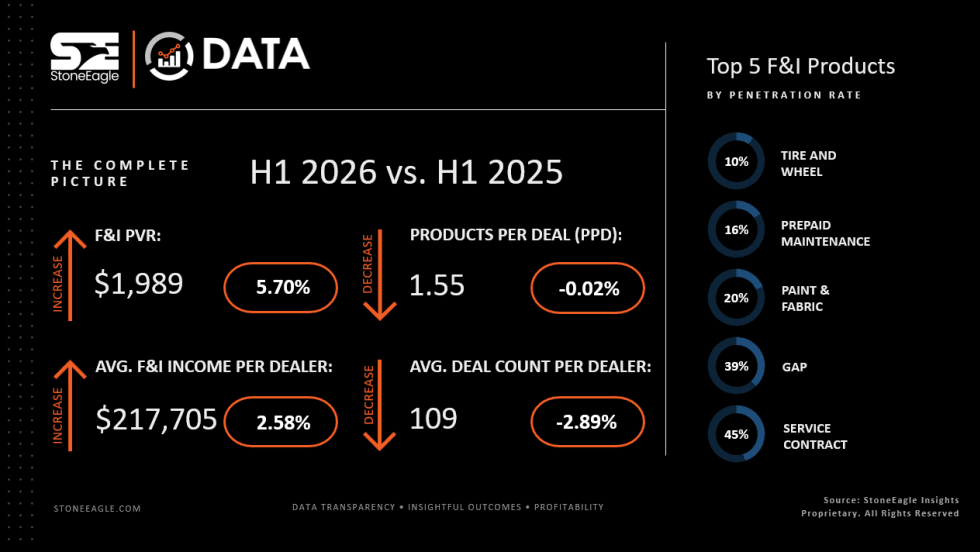
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →