

‘Great Deleveraging’ Has Ended, Equifax Reports
Consumers are back in the borrowing business, with November consumer credit data from Equifax showing that nonmortgage credit balances rose to their highest level in five years.
ATLANTA — Based on consumer credit data collect by Equifax through November, the five-year run of debt deleveraging might be over. The credit reporting agency reported this week that nonmortgage credit balances reached their highest level since the Great Recession in November, totaling $3.1 trillion. Showing the biggest increase were credit balances for auto loans.
Credit balances for auto loans increased 9.6% on a year-over-year basis to $965 billion. Credit balances for retail- and bank-issued credit cards also increased 4.8% and 4.7% to $71 billion and $611.7 billion, respectively.
November also saw the total balance of nonmortgage write-offs fall to their second lowest level in eight year on a year-to-date basis, totaling $73.4 billion. The total balance of home-finance write-offs also fell to their second-lowest level in eight years on a year-to-date basis, totaling $91.2 billion.
"The Great Deleveraging has clearly ended and U.S. consumers are back in the borrowing business, but how they borrow has greatly changed from prior to the Great Recession," said Amy Crews Cutts, senior vice president and chief economist at Equifax. "Today, while auto loans make up 30.9% of nonmortgage consumer debt — just as they did in December 2007 at the recession's start — student loans have grown from 20.2% to a whopping 37.3%, and bank- and retailer-issued credit cards are down to 21.9% of consumer debt from 31.4%."
Equifax also reported that the total number of outstanding loans on a year-to-date basis in November was more than 70 million, the highest level in more than five years. Serious delinquencies, or auto loans 60 days or more past due, accounted for 1.04% of total balances — a decrease from 1.15% one year ago.
Additionally, the total number of new auto loans originated between January and September 2014 was 19.2 million, an increase of 4.7% from a year ago, according to Equifax. At the same time, the total balance of new credit originated was $391.6 billion, an increase of 7%.
"One way to read this change is that consumers now value investment (in their education and durable goods like cars) over immediate consumption, which is good for our economy over the long run,” Cutts noted. “But with the exception of new car production, sluggish consumption slows economic growth in the short-term, partially explaining the slower-than-hoped-for economic recovery."
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →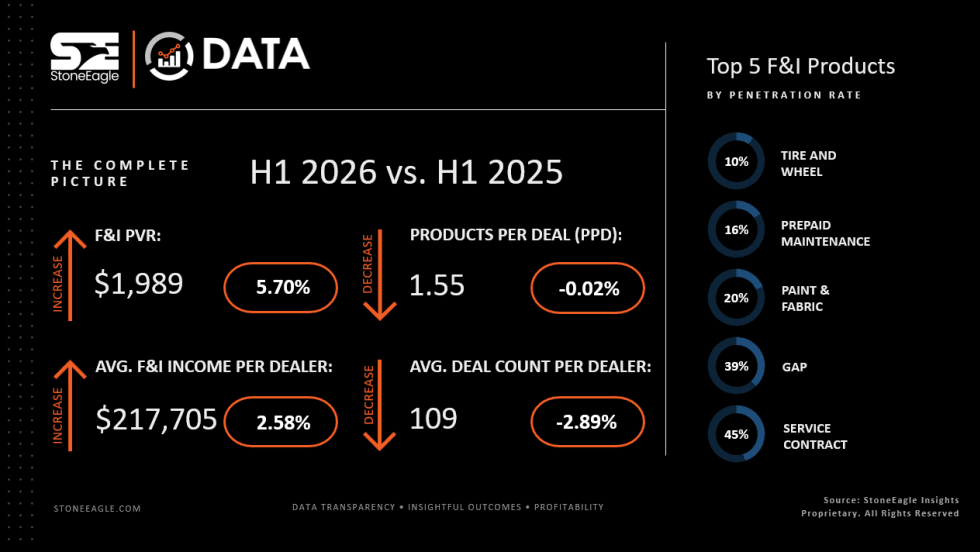
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →