

CFPB Methodology Flawed, New Study Concludes
A new study released by the American Financial Services Association finds bias and high error rates in the CFPB's proxy methodology for determining disparate impact.
WASHINGTON — A comprehensive study of more than 8.2 million auto financing contracts found that the disparity alleged by the Consumer Financial Protection Bureau (CFPB) between the amount of dealer reserve charged to minorities and non-minorities is not supported by data.
The study, “Fair Lending: Implications for the Indirect Auto Finance Market,” was commissioned by the American Financial Services Association (AFSA) and conducted by Charles River Associates. It examined the proxy methodology used by the CFPB and found significant bias and high error rates.
“The AFSA’s results are much lower than what the CFPB alleges as problematic in the marketplace, because the association’s study factored in complexities of the automotive market that the CFPB did not consider, and errors associated with the CFPB methodology,” AFSA President & CEO Chris Stinebert said. “The interplay between factors such as geography, new versus used, length of loan, down payment, trade-in vehicle, credit score and competitive factors, such as meeting or beating a competing offer, is evidence of a dynamic market.”
Central to the study was an examination of the Bayesian Improved Surname Geocoding (BISG) proxy methodology used by the CFPB to determine disparate impact to legally protected groups.
BISG estimates race and ethnicity based on an applicant’s name and census data. The AFSA’s study calculated BISG probabilities against a test population of mortgage data, where race and ethnicity are known. Among the findings:
When the proxy uses an 80% probability that a person belongs to an African American group, the proxy correctly identified their race less than 25% of the time.
Applying BISG on a continuous method overestimates the disparities and the amount of alleged harm and provides no ability to identify which contracts are associated with the allegedly harmed consumers.
“Alleged pricing discrepancies between minorities and nonminorities for auto financing rates are simply not supported by data,” Stinebert said. “We have reviewed our study results with the CFPB and look forward to continuing our work with the bureau to address the issues we raised and to ensure consumers have access to affordable credit.”
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →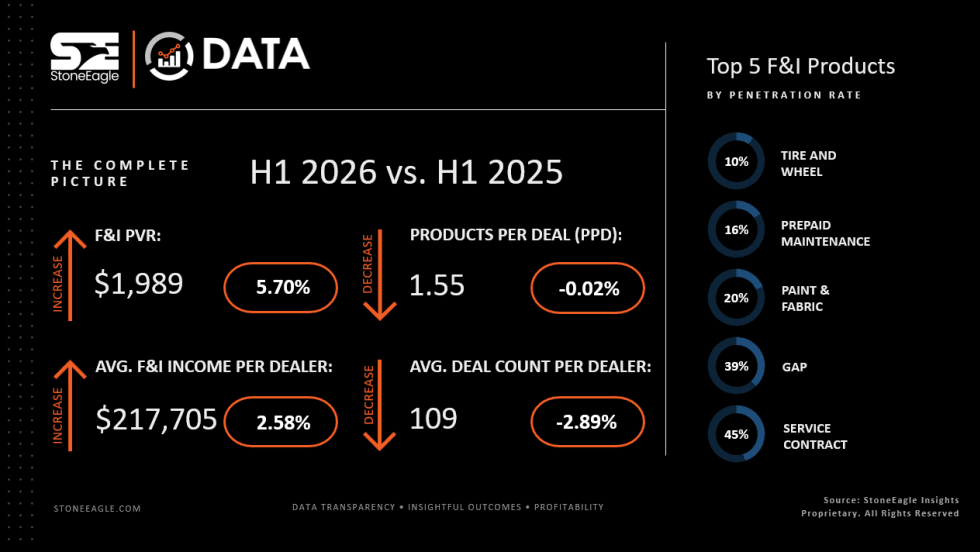
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →