

Darwin Updates F&I Platform to Address Military Lending Act Rules
Darwin today announced a new update to its F&I sales platform designed to address the interpretive rule the Defense Department issued last month under the MLA.
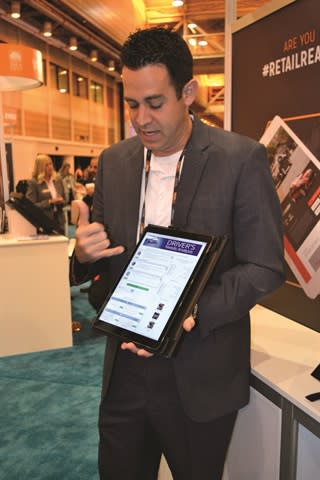
ISELIN, N.J. — F&I software maker Darwin Automotive today announced the integration of smart disqualify technology into its F&I platform. The update, which disqualifies F&I products based on Military Lending Act qualifications, was designed to address an interpretive rule the Department of Defense (DOD) issued on Dec. 15 under the MLA.
The DOD’s rule amended three of the “Q&A” format interpretations — and added one — it issued in August 2016 regarding compliance with its July 2016 final rule implementing regulations of the MLA — the first of which clarified that including credit-protection products like GAP in a servicemember’s vehicle finance contract would take the transaction outside the scope of the motor vehicle financing exclusion and subject it to a slew of restrictions and requirements under the MLA.
The interpretive rule also applies to a servicemember’s dependents and is retroactive to Oct. 3, 2015 — the latter putting both dealers and finance sources in regulatory jeopardy.
“With Darwin, the needs of a consumer are paramount in determining which products and services can best fit those needs,” said Darwin CEO Phillip Battista. “Out of respect to the men and women who have served, we want to provide the highest possible level of transparency at no cost and have integrated MLA qualification screening into our Darwin platform at no charge to our dealer and lender clients.”
Passed by Congress in 2006, the MLA provides specific protections for active duty servicemembers and their dependents in consumer credit transactions, including a 36% cap on the military annual percentage rate in covered transactions. It also requires military-specific disclosures and prohibits creditors from requiring arbitration in the event of a dispute, among many other protections.
When the MLA first took effect, by regulation it only covered three narrow categories of consumer credit. Credit transactions involving the financing of a motor vehicle or personal property when the credit is secured by the vehicle or property were statutorily exempted.
When the DOD amended its implementing rule in July 2015, the MLA’s protections were expanded to other types of consumer credit, although the motor vehicle finance exemption remained. However, shortly after the expanded rule took effect on Oct. 3, 2016, the DOD issued an interpretation of the personal property financing exclusion. It stated that financing items beyond the personal property being financed took the transaction outside the scope of the personal property exception to the MLA’s requirements.
That interpretation raised the question of whether the DOD had a similar view of the identically worded motor vehicle financing exclusion. In last month’s interpretive rule, the DOD said the answer depends on what the credit beyond the purchase price is used to finance. It then listed examples of items that don’t qualify for the exclusion, including credit-production products like GAP and credit insurance, as well as cash-out financing.
The MLA’s final rule does allow creditors, including dealers, to conclusively check whether a credit applicant is or is not a servicemember or a dependent of a servicemember through a credit reporting agency or the DOD’s own database.
As for Darwin’s new update, company officials said a new question was added to the interview portion of its F&I platform. It asks customers if they’re an active duty servicemember or a dependent of an active duty servicemember. If the answer is “Yes,” the company’s smart disqualify technology automatically removes products that would subject the deal to the MLA’s rules and restrictions — eliminating the need for the business manager to manually build or edit the menu.
“If a vehicle finance contract for active military members or their dependents includes financing for credit-related products or services, such as GAP or other types of credit insurance, or provides cash-out financing, the creditor, which would be the dealership or lender, must comply with the act,” Battista said. “Products and services such as upgraded in-vehicle technology or extended warranties are related to the vehicle and are exempt from the rule. But credit-related products and services, such GAP and credit life insurance, are related to the finance transaction, not the vehicle, so they are included under the act.”
More F&I
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →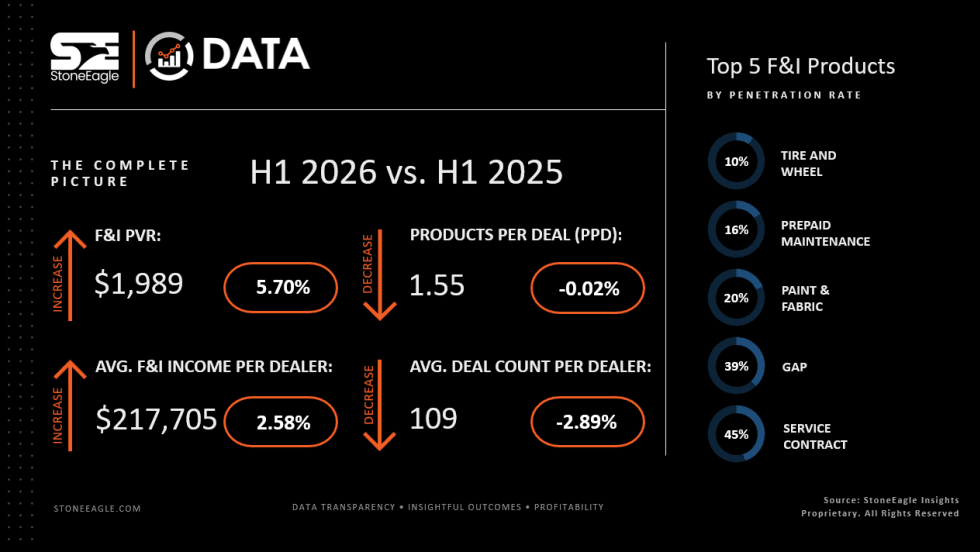
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Leading with Purpose
In this video, Trent White explains how understanding your people’s 'why' is a key leadership responsibility of F&I professionals and how that mindset drives dealership engagement, trust and performance.
Read More →
Integrating Nontraditional F&I Products
The niche presents a strategic advantage for auto dealerships as they move to adapt to fast-changing consumer expectations in today’s market.
Read More →