

November SAAR Highest Since December 2007, TrueCar Reports
November’s SAAR reached its highest level since the start of the Great Recession, and TrueCar predicts even bigger things for December.
SANTA MONICA, Calif. — November vehicle sales increased a very healthy 15 percent vs. a year ago, TrueCar reported this week. According to its data, November resulted in a 15.54 million SAAR, the highest since December 2007.
TrueCar estimates that the aftermath of Sandy contributed at least 30,000 additional sales to November sales totals. The company expects those numbers to increase in December.
“November was one of the strongest months in over four years and we project that December could end up being a bigger month,” said Jesse Toprak, senior analyst for TrueCar.com. “Combination of great products and attractive finance/lease promotions in addition to a boost from replacement demand created by Sandy will ensure a solid finish to the best year in car sales since 2007.”
Nissan had the biggest sequential monthly sales (up 21 percent) and market share increase in November, surpassing Hyundai/Kia in the firm’s industry sales ranking for the month. TrueCar also found the gap between the top three automakers in the U.S. narrowed in November, particularly with Ford coming within about 9,000 units of GM for the top spot.
TrueCar also noted rise in average transaction prices, which reached an all-time high of $30,832. Chrysler had the highest ratio of incentives/ATP at 10.6 percent, while Toyota had the lowest at 6.6 percent. The industry average was 8.2 percent, down from 8.6 percent a year ago.
TrueCar’s December early forecast shows the month tracking at 1.43 million units, adding up to 14.56 million total units sold for 2012. TrueCar's 2013 forecast is 15.4 million units. Large trucks could have the highest unit sales in December since 2008 due to increased incentive spending by automakers.
Unit Sales
Manufacturer | November 2012 | % Change vs. October 2012 | % Change vs. November 2011 |
Chrysler | 122,565 | -2.9% | 14.4% |
Ford | 177,092 | 5.4% | 6.4% |
GM | 186,505 | -4.7% | 3.4% |
Honda | 116,580 | 9.0% | 38.9% |
Hyundai/Kia | 94,542 | 2.0% | 9.1% |
Nissan | 96,197 | 20.7% | 12.9% |
Toyota | 161,695 | 4.2% | 17.2% |
Volkswagen | 48,795 | 6.0% | 28.0% |
Industry | 1,142,883 | 4.7% | 15.0% |
Market Share
Manufacturer | November 2012 | October 2012 | November 2011 |
Chrysler | 10.7% | 11.6% | 10.8% |
Ford | 15.5% | 15.4% | 16.7% |
GM | 16.3% | 17.9% | 18.1% |
Honda | 10.2% | 9.8% | 8.4% |
Hyundai/Kia | 8.3% | 8.5% | 8.7% |
Nissan | 8.4% | 7.3% | 8.6% |
Toyota | 14.1% | 14.2% | 13.9% |
Volkswagen | 4.3% | 4.2% | 3.8% |
Incentive Spending
Manufacturer | November 2012 Incentives | % Change vs. October 2012 | % Change vs. November 2011 |
Chrysler | $3,147 | 1.5% | -3.1% |
Ford | $2,681 | 6.3% | -8.3% |
GM | $2,864 | -1.7% | -7.6% |
Honda | $2,132 | 13.3% | -8.6% |
Hyundai/Kia | $1,488 | 8.2% | 21.3% |
Nissan | $2,890 | 21.7% | -2.0% |
Toyota | $1,885 | 16.2% | -0.7% |
Volkswagen | $2,392 | 5.7% | -4.5% |
Industry | $2,518 | 9.4% | -4.3% |
Average Transaction Prices
Manufacturer | November 2012 Transaction Price | October 2012 Transaction Price | November 2011 Transaction Price | Percent Change November 2011 to November 2012 | Percent Change October 2012 to November 2012 | |
Chrysler (Chrysler, Dodge, Jeep, Ram, Fiat) | $29,796 | $29,541 | $29,071 | 2.5% | 0.9% | |
Ford (Ford, Lincoln) | $32,543 | $32,141 | $31,498 | 3.3% | 1.3% | |
GM (Buick, Cadillac, Chevrolet, GMC) | $32,891 | $32,547 | $33,027 | -0.4% | 1.1% | |
Honda (Acura, Honda) | $26,897 | $27,011 | $26,529 | 1.4% | -0.4% | |
Hyundai/Kia | $22,342 | $22,410 | $21,265 | 5.1% | -0.3% | |
Nissan (Nissan, Infiniti) | $27,704 | $27,652 | $27,770 | -0.2% | 0.2% | |
Toyota (Lexus, Scion, Toyota) | $28,396 | $27,910 | $27,442 | 3.5% | 1.7% | |
Volkswagen (Audi, Volkswagen) | $33,610 | $33,408 | $33,004 | 1.8% | 0.6% | |
Industry | $30,832 | $30,486 | $30,497 | 1.1% | 1.1% | |
Manufacturer | November 2012 Incentives/Avg. Transaction Price | October 2012 Incentives/Avg. Transaction Price | November 2011 Incentives/ Avg. Transaction Price | Percent Change November 2011 to November 2012 | Percent Change October 2012 to November 2012 |
Chrysler (Chrysler, Dodge, Jeep, Ram, Fiat) | 10.6% | 10.5% | 11.2% | -0.6% | 0.1% |
Ford (Ford, Lincoln) | 8.2% | 7.8% | 9.3% | -1.0% | 0.4% |
GM (Buick, Cadillac, Chevrolet, GMC) | 8.7% | 9.0% | 9.4% | -0.7% | -0.2% |
Honda (Acura, Honda) | 7.9% | 7.0% | 8.8% | -0.9% | 1.0% |
Hyundai/Kia | 6.7% | 6.1% | 5.8% | 0.9% | 0.5% |
Nissan (Nissan, Infiniti) | 10.4% | 8.6% | 10.6% | -0.2% | 1.8% |
Toyota (Lexus, Scion, Toyota) | 6.6% | 5.8% | 6.9% | -0.3% | 0.8% |
Volkswagen (Audi, Volkswagen) | 7.1% | 6.8% | 7.6% | -0.5% | 0.3% |
Industry | 8.2% | 7.5% | 8.6% | -0.5% | 0.6% |
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →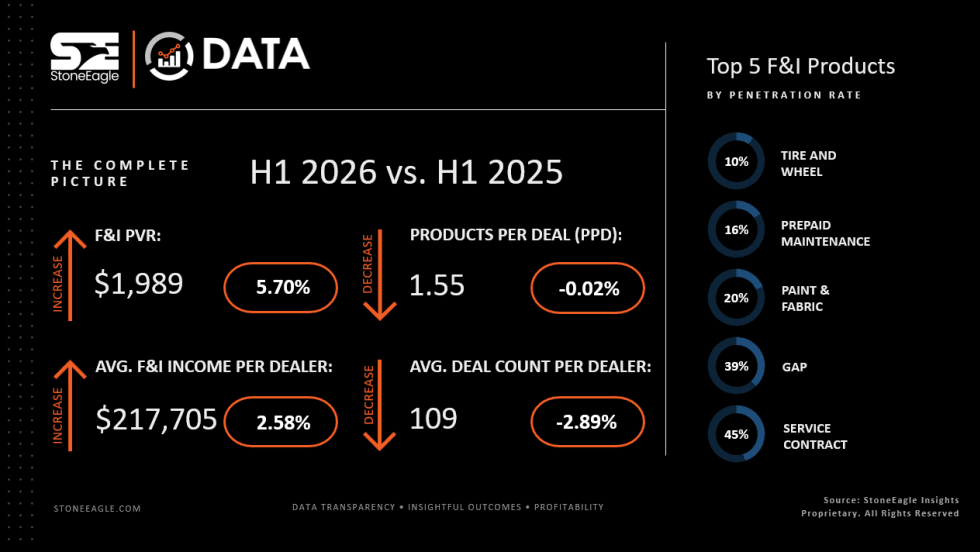
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →