

Ohio Dealers Settle FTC’s Deceptive Advertising Charges
The FTC announced this week that it has reached an agreement with two Ohio dealers to settle charges that their lease advertisements violated the FTC Act and the Consumer Leasing Act’s Regulation M.
WASHINGTON, D.C. — Two Ohio dealers have agreed to settle Federal Trade Commission (FTC) charges that they deceived consumers with advertisements that touted low monthly car lease payments but failed to disclose key terms of the offers.
The FTC’s administrative complaint alleged that Progressive Chevrolet and Progressive Motors Inc. of Masillon, Ohio, failed to properly disclose terms such as the total amount due at signing, whether a security deposit was required, and credit score requirements. According to the regulator, “typical consumers could not qualify for the advertised terms.
The dealers were charged with violating the FTC Act and the Consumer Leasing Act’s Regulation M. Progressive Chevrolet Company also does business as Progressive Auto Group and Progressive Motors Inc.
The proposed settlement order, which will remain in effect for 20 years, prohibits the dealers from advertising misleading lease or finance terms. It also requires them to clearly and conspicuously disclose all qualifications or restrictions on a consumer’s ability to obtain the advertised terms.
“If the ad states that consumers must meet a certain credit score in order to qualify for the offer and a majority of consumers are not likely to meet the stated credit score, the ad must clearly and conspicuously disclose that fact,” the FTC stated in its release.
The dealers are also barred from advertising a payment amount, or that any or no initial payment is required without clearly disclosing that the transaction is a lease; the total amount due at consummation or delivery; the number of payments and their amounts and timing; whether or not a security deposit is required; and that there may be an extra charge at the end of the lease where the consumer’s liability is based on the difference between the vehicle’s residual value and its value at the end of the lease.
The commission’s vote to issue an administrative complaint and accept the proposed consent agreement was 4-0. The agreement will be subject to public comment for 30 days after it is published in the Federal Register. After that, the commission will decide whether to issue the order on a final basis.
More F&I
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →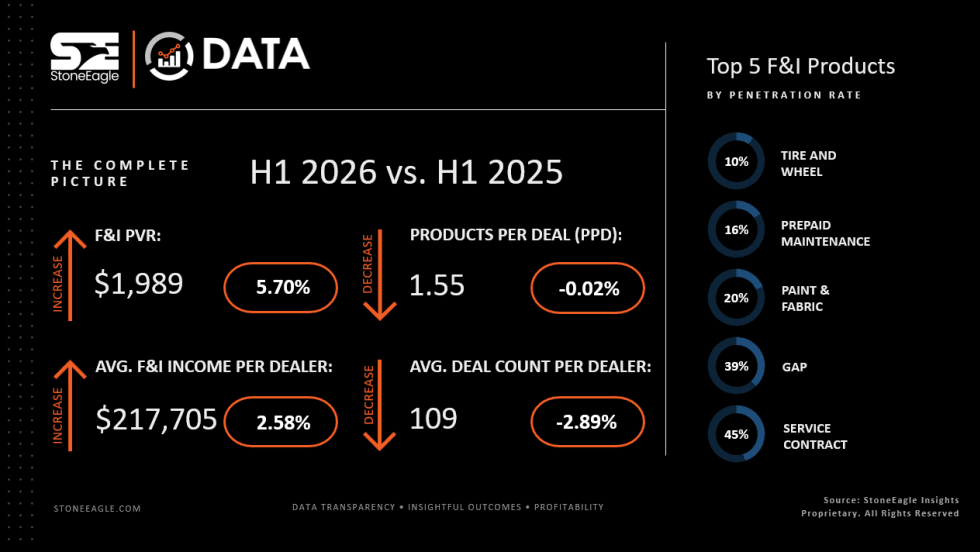
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Leading with Purpose
In this video, Trent White explains how understanding your people’s 'why' is a key leadership responsibility of F&I professionals and how that mindset drives dealership engagement, trust and performance.
Read More →
Integrating Nontraditional F&I Products
The niche presents a strategic advantage for auto dealerships as they move to adapt to fast-changing consumer expectations in today’s market.
Read More →