



Q2 Subprime Originations Exceed Pre-Recession Levels, Experian Reports
Subprime lending was on the rise in the second quarter, but Experian Automotive noted that lenders kept loan-to-value ratios in check.
SCHAUMBURG, Ill. — Auto loans made to credit-challenged customers in the second quarter accounted for more than one in four new-vehicle loans originated, Experian Automotive reported. But finance sources did show that they aren’t necessarily throwing caution to the wind.
Experian Automotive noted that loans made to customers with nonprime, subprime and deep subprime credit accounted for 25.41 percent of all new-vehicle loans originated during the quarter, a 14 percent increase from a year ago. New-vehicle loans made to credit-challenged customers also were higher than they were during the second quarter of 2007 (24.96 percent) and Q2 2008 (24.49 percent).
However, the Q2 analysis also showed that lenders are still taking a cautious approach, keeping loan-to-value (LTV) ratios lower than they were a year ago. For new vehicles, the average LTV ratio was 109.55 percent vs. 115.65 percent in the second quarter of 2011.
“Despite the rise in subprime loans overall, there is still a strong sense of managing risk,” said Melinda Zabritski, director of automotive credit for Experian Automotive. “Because the overall lending environment has improved, lenders are making loans available to a wider range of customers. This is good for manufacturers and dealers, as it allows them to sell more vehicles. However, the lower loan-to-value ratios show that lenders are not willing to throw caution to the wind.”
Additionally, the Q2 report showed that the average customer credit score for new-vehicle loans dropped nine points, from 762 in the second quarter 2011 to 753. For used-vehicle loans, the average customer credit score also dropped nine points from 671 in the second quarter 2011 to 662.
The following are other data points from the second quarter:
• The average amount financed for a new vehicle increased $474, from $25,240 in Q2 2011 to $25,714 in Q2 2012.
• The average amount financed for a used vehicle jumped $370 from $17,063 in Q2 2011 to $17,433 in Q2 2012.
• The average monthly payment for both new and used vehicles was relatively flat, with new vehicles rising by $2, from $450 in Q2 2011 to $452 in Q2 2012. For used vehicles, monthly payments jumped $4, from $347 in Q2 2011 to $351 in Q2 2012.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →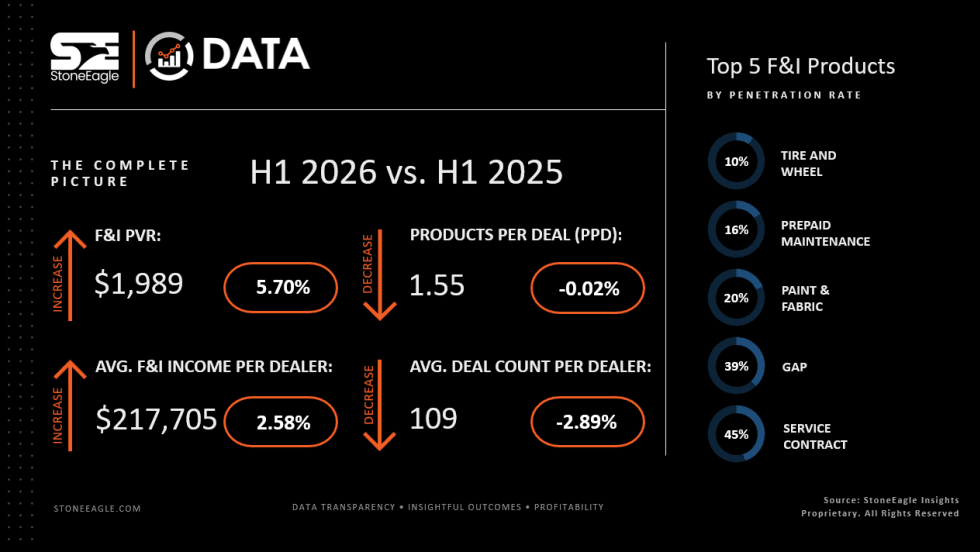
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →