



Reuters: U.S. Senate Panel Plans to Scrap CFPB’s Dealer Participation Guidance
U.S. Senate Banking Committee Republican Pat Toomey said on Tuesday the panel plans to scrap the CFPB’s guidance on dealer participation and leverage lending.
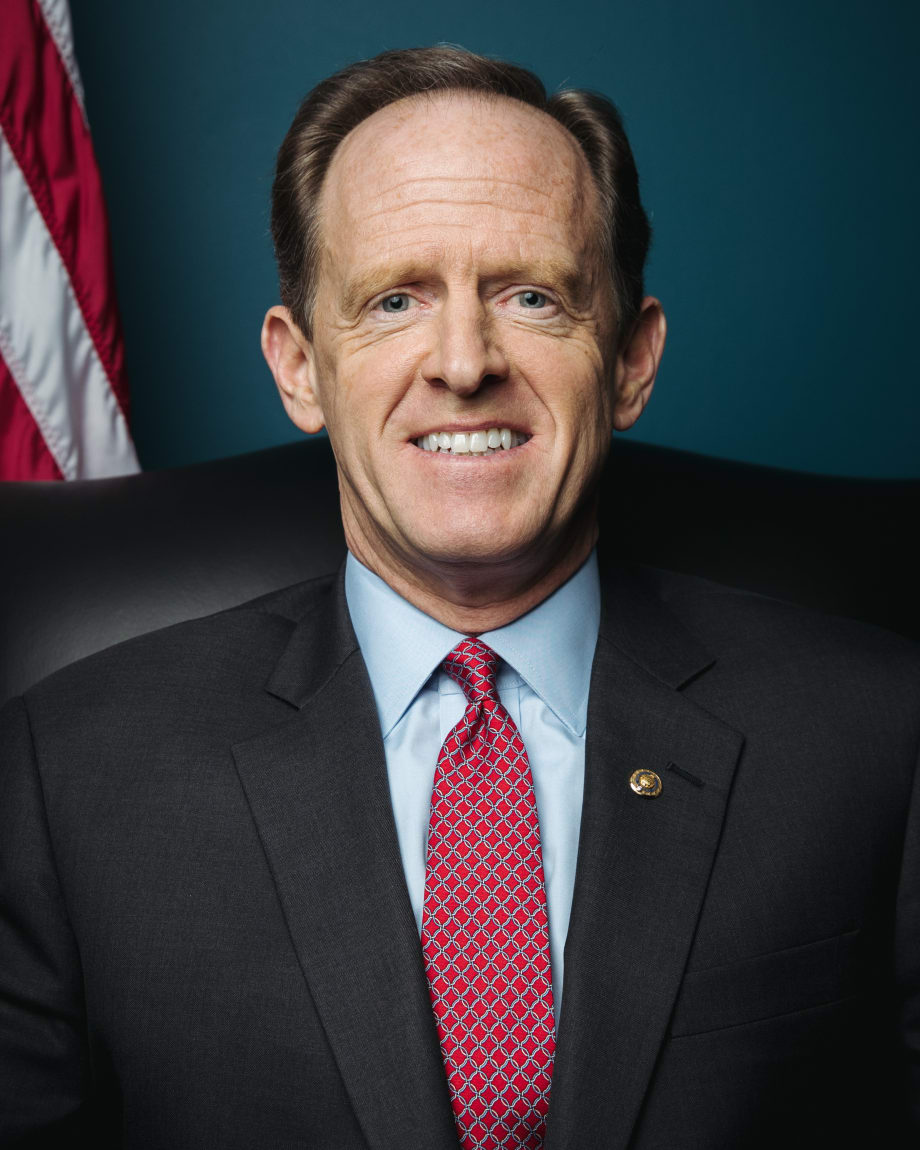
WASHINGTON, D.C. — Less than five months after the Government Accountability Office (GAO) agreed with his view that Congress has the power to repeal two Consumer Financial Protection Bureau (CFPB) rules, including its controversial guidance on dealer participation, U.S. Senator Banking Committee Republican Pat Toomey said the panel plans to do just that in the coming weeks, according to a Reuters report.
Toomey, who was addressing community bankers in Washington to lobby lawmakers to vote in favor of a bill that would reduce compliance obligations for smaller financial institutions, had asked the GAO last March whether the CFPB’s guidance on dealer participation and leveraged lending falls under the Congressional Review Act. The GAO said they did, setting the table for the Republican-controlled Congress to pass joint resolutions of disapproval under the CRA to repeal both rules — a process similar to the one used to repeal the bureau’s rule on forced arbitration last October.
“GAO’s decision is an important reminder that agencies have a responsibility to live up to their obligations under the law. When they don’t, Congress should hold them accountable,” Toomey said in December after the GAO delivered its response. “I intend to do everything in my power to repeal this ill-conceived rule using the Congressional Review Act.”
On Tuesday, according to the Reuters’ report, Toomey said the Senate Banking Committee would scrap the rule, referring to the bureau’s March 2013 auto lending rule.
The CFPB alleged in its five-page fair lending guidance that bank policies which allow auto dealers to mark up interest rates on retail installment sale transactions as compensation for services rendered create a significant risk of unintentional, disparate impact discrimination. It also warned lenders active in the indirect auto finance channel that they would be held liable for unlawful, discriminatory markups.
Auto finance trade groups have argued that the bureau used its guidance to indirectly regulate the activities of dealers, which are mostly exempt from the bureau’s oversight under the Dodd-Frank Act. Since issuing its guidance, the bureau has imposed millions of dollar in fines on auto finance sources, including Ally Financial, American Honda Finance Corp., and Fifth Third Bank.
Congress has attempted to kill the bureau’s guidance through the legislative route. In November 2015, the House of Representatives approved the Reforming CFPB Indirect Auto Finance Guidance Act by a 332-96 vote. The bill, however, was not acted upon by the Senate before the end of the 114th Congress.
When it initially issued its guidance, the bureau argued that because it had no legal effect on regulated entities, the CRA does not apply. The GAO, however, stated in its response to Toomey’s request that the bulletin “fits squarely within the Supreme Court’s definition of a statement of policy,” because it provides information on the manner in which the bureau planned to exercise its discretionary enforcement power.
And according to the GAO, the CRA “establishes special expedited procedures under which Congress may pass a joint resolution of disapproval that, if enacted into law, overturns the rule. Legal insiders, however, say the GAO’s findings give the bureau’s acting director all the authority he needs to rescind the guidance. Mick Mulvaney, who was appointed acting director this past November after Richard Cordray stepped down as the bureau’s director, has yet to act on that authority.
More F&I

How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →
Leading with Purpose
In this video, Trent White explains how understanding your people’s 'why' is a key leadership responsibility of F&I professionals and how that mindset drives dealership engagement, trust and performance.
Read More →
Integrating Nontraditional F&I Products
The niche presents a strategic advantage for auto dealerships as they move to adapt to fast-changing consumer expectations in today’s market.
Read More →
Trust Is Personal
Technology, no matter how efficient, can’t replace what the human F&I manager can do, which is to bridge the divide between cyberspace and the in-store experience.
Read More →