



U.S. Banks Loosen Terms on Business, Car Loans
U.S. banks are responding to increased demand for credit by relaxing guidelines on car loans and credit cards, the Federal Reserve reports.
WASHINGTON — U.S. banks have made it slightly easier for companies to obtain loans and for consumers to get car loans and credit cards, according to a survey released Monday.
The Federal Reserve’s senior loan officer survey didn’t report a big change in lending, with most banks indicating that lending standards remain unchanged for business loans despite growing demand. But a small percentage of banks did indicate that standards are easing, and that they have extended more favorable terms to borrowers who attained loans.
Peter Newland, economist at Barclays Capital, called the report “mildly positive.” He said that banks are slowly loosening terms, but without major changes in recent quarters.
Credit standards tightened sharply in the 2007-to-2009 recession, and any loosening of terms would help the recovery. Economists disagree on how damaged the credit channel remains. The Fed survey of 64 domestic lenders and 23 U.S. branches of foreign banks was established to help gauge the willingness of banks to lend and the demand that they were seeing.
Joseph LaVorgna, chief U.S. economist at Deutsche Bank, said bank credit has been expanding “quite quickly.” He noted that lending on commercial and industrial loans is up 12 percent over the past 12 months, the fastest rate since October 2008.
According to the Fed survey, lending standards were eased due to more aggressive competition from other banks and nonbank lenders and not because of a more favorable economic outlook. See full Fed survey.
Small firms did not benefit from the easing of lending terms, the survey found. Demand for loans from small business was also unchanged. The report also indicated that U.S. banks continue to tighten their lending standards to European banks as a result of the debt crisis, the Fed survey found.
In the consumer sector, there were reports of strong demand for prime and nontraditional mortgages. Newland of Barclays said the pickup in demand for mortgage loans showed that a gradual housing sector recovery remains in place.
Some banks reported that they had eased standards of auto loans and credit-card loans in response to growing demand. In May, consumer credit rose at an annual rate of 8 percent, the Federal Reserve reported last month.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →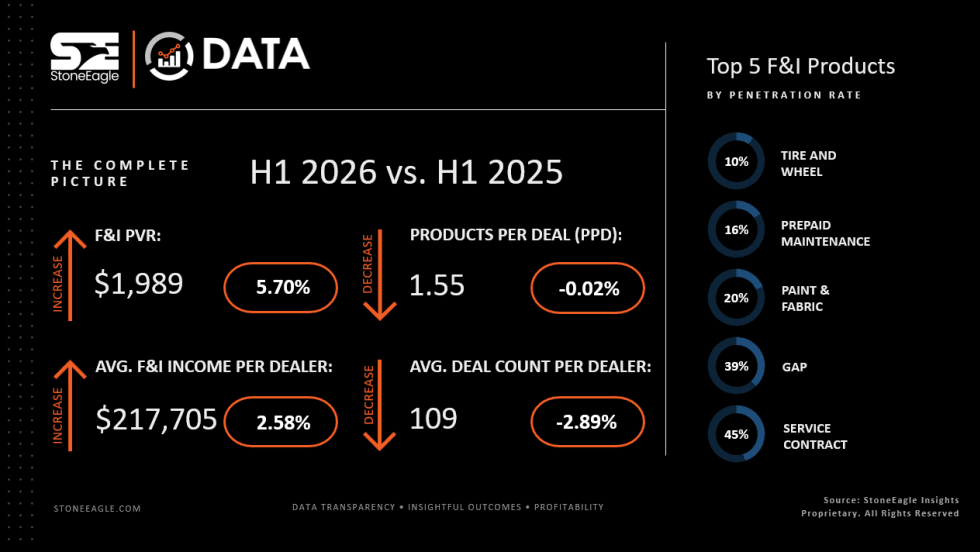
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →