

Equifax: Auto Loan Balance Hits 5-Year High
The balance of auto loans in August increased 9.7 percent from last year, rising from $760.8 billion to $834.4 billion, according to Equifax’s National Consumer Credit Trends Report.
ATLANTA — The total outstanding balances on auto and credit card loans realized a year-over-year increase in August, according to Equifax's latest National Consumer Credit Trends Report.
The total balance of existing auto loans is at its highest level in more than five-years, increasing 9.7 percent from a year ago to $834.4 billion. Balances on bank-issued credit cards increased (0.2 percent to $537.8 billion) for the second consecutive month — the first time in five year. Equifax also reported that retail card balances notched 24 consecutive months of year-over-year growth, rising 7 percent in August to $55.9 billion.
In addition, auto and credit card portfolios are the only two major segments in which rising balances accompany improving delinquency rates. Year-over-year changes in the 60-day plus delinquency rates, as a percentage of total balances outstanding, include:
Auto: decreased more than 10 percent (from 1.28 percent to 1.14 percent);
Bank credit card: decreased more than 13 percent (from 2.10 percent to 1.81 percent); and
Retail credit card: decreased 0.9 percent (from 3.37 percent to 3.34 percent)
"Our data consistently indicates that the American consumer is being very disciplined in their use of credit. It's like they've gone on a debt-diet and they are really sticking to it, with modest increases in line with capacity to repay," said Equifax Chief Economist Amy Crews Cutts.
Excluding student loans, total consumer debt is down 15 percent from its peak, Cutts added. Delinquency rates outside of home and student loans have returned to pre-recession levels.
“Economic conditions are causing the lingering high default rates on student loans and mortgages, and hopefully we will see those improve more quickly in coming months," she said.
Other highlights for the auto segment include:
The total number of loans outstanding in August 2013 is more than 61 million, a 57-month high;
By source, loans funded by banks, savings and loans or credit unions are at $401.7 billion, while the total number of loans is 29.5 million — a five-year high for both;
The total outstanding balance for loans funded by auto finance companies is $432.7 billion, a 56-month high, while the total number of existing loans is more than 31.8 million, its highest level in 54-months; and
The total balance of auto loan originations year-to-date in June 2013 is 237.6 billion, an increase of nearly 15 percent from same time a year ago and the most new credit originated for that time period in more than eight years.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →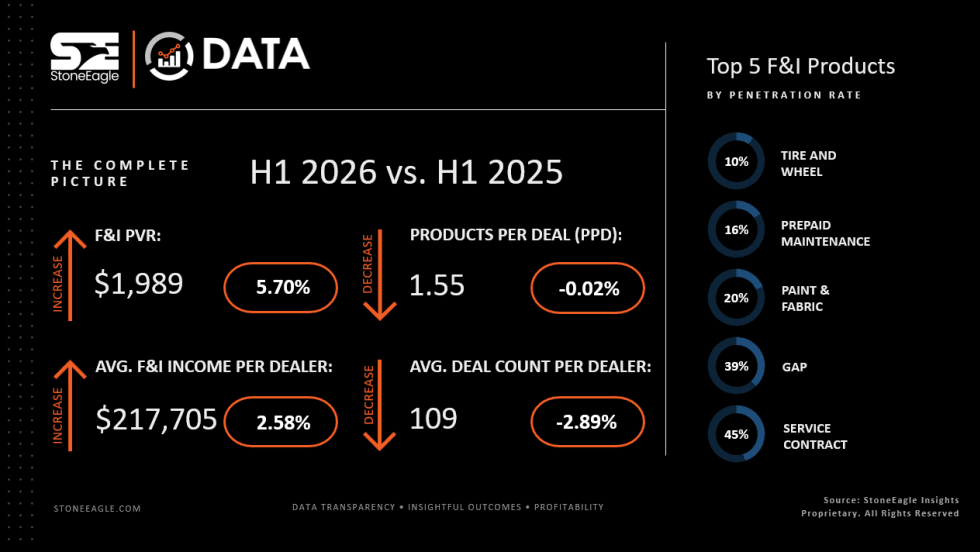
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →