

Gov. Cuomo to Credit Reporting Agencies: Protect Sandy Victims
New York Gov. Andrew Cuomo is demanding that credit bureaus give special allowances for Hurricane Sandy victims. The credit reporting agencies, however, say they are already doing their part.
ALBANY, N.Y. — New York Governor Andrew Cuomo called on credit reporting agencies last week to not allow credit scores for Hurricane Sandy victims to suffer, but a trade group representing the agencies said it’s up to finance sources to make allowances for consumers affected by last October’s superstorm.
At the direction of the governor, Superintendent of Financial Services Benjamin M. Lawsky sent letters to FICO, Equifax, Experian, TransUnion and the Consumer Data Industry Association (CDIA), requesting that they ensure that credit scores for Hurricane Sandy victims not be ruined by the natural disaster because it was out of their control.
“We request that your organization ensure that no Sandy victim's credit is unfairly damaged due to circumstances beyond their control,” the letter states, in part. “We are also asking that you reset any scores that have already been improperly lowered. We are also going to work with the banks and other financial institutions to ensure they are doing their part to avoid these unfair results.”
Equifax and the CDIA responded, saying that they have no control over what happens to credit scores. They added that any special allowances for disaster victims are in the hands of individual lenders and score developers such as FICO or VantageScore.
However, the CDIA reportedly sent three separate advisories to its group of 8,000 credit card issuers, lenders, members of the American Bankers Association and other entities furnishing data to nationwide credit bureaus — one issued the day after Hurricane Sandy hit, another in January, and the latest one issued last week upon the request from Lawsky.
According to Equifax Spokesperson Tim Klein, the notices focused on two actions, one of which draws on a practice that has been in place since 2005, when credit bureaus reacted to Hurricane Katrina. The bureaus adopted a special disaster code at the time “to specifically deal with natural disasters and their impact on an individual’s credit history so that subsequent recipients of a credit report can take this into account when making a decision about a loan, apartment rental or other transaction.”
The advisories from the CDIA also addressed situations where finance sources place a customer’s loan into forbearance. According to Klein, if the lender reports that to the credit bureau, the loan should remain current so that consumers’ credit scores are not adversely impacted.
“The CDIA’s members were proactive in their outreach to ensure that lenders understood their data reporting options,” Klein stated in the e-mail. “The CDIA is the owner and administrator of the ‘Metro 2’ data reporting system, which is used by all data furnishers to report data to the credit bureaus. This format enables lenders to provide data in a uniform and consistent manner.”
Norm Magnuson, a spokesperson with the CDIA, iterated that the organization does not personally develop consumers’ scores, but it does have access to the financial institutions that make the decisions on consumers’ credit scores. “We’ve engaged with the governor’s office about what we’ve done and what we continue to do,” he said. “We’re going to help in any way we can.”
FICO also agreed to meet with N.Y. state officials. “FICO deeply sympathizes with the victims of Hurricane Sandy. We would be happy to discuss with State Superintendent Lawsky, lenders and consumer reporting agencies how best to address the continuing financial challenges faced by victims of that disaster,” FICO spokesperson Anthony A. Sprauve wrote in an e-mail to F&I and Showroom.
Governor Cuomo’s office did not respond to the status of any resolution. Representatives from Experian and TransUnion were unavailable for comment.
— Stephanie Forshee
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →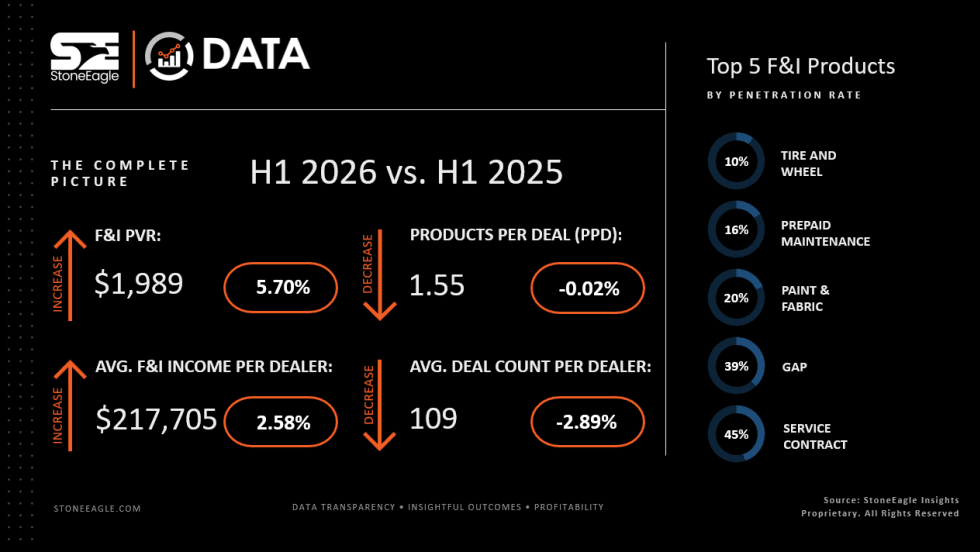
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →