

Trade Groups Ask HUD, CFPB to Clarify Use of Disparate Impact Theory
Eight trade associations request that the Department of Housing and Urban Development and the Consumer Financial Protection Bureau clarify and create guidance related to their use of the disparate impact theory to determine discrimination.
WASHINGTON — Eight trade associations sent a letter to Department of Housing and Urban Development (HUD) Secretary Shaun Donovan and Consumer Financial Protection Bureau (CFPB) Director Richard Cordray requesting guidance and clarity on the bureau’s use of disparate impact, a legal theory the CFPB recently evoked to target auto lending.
According to the letter, the HUD recently finalized a regulation under the Fair Housing Act that expressly provides for liability for a facially neutral mortgage lending or servicing practice that has a disparate impact, or “discriminatory effect,” upon a protected class, even in the absence of any intention to discriminate.
The CFPB similarly stated in recent guidance that a disparate impact theory of discrimination applies to and will create liability under the Equal Credit Opportunity Act (ECOA).
The letter was signed by the American Bankers Association, American Financial Services Association, Consumer Bankers Association, Consumer Mortgage Coalition, Housing Policy Council of The Financial Services Roundtable, Independent Community Bankers of America, Mortgage Bankers Association and U.S. Chamber of Commerce.
“While we question the legal foundations underlying HUD’s final rule, especially the burden shifting standards, this letter seeks clarity on how the rule interacts with other requirements since the disparate impact liability concerns appear incompatible with other federal standards,” the letter reads. “Members of the associations seek written guidance from HUD and the CFPB so that mortgage lenders and servicers are able to meet their responsibilities under all mortgage lending standards.
“Given the significant amount of uncertainty created by the final disparate impact rule and its intersection with the CFPB’s mortgage rules, we urge you to set out written guidance for the industry that makes clear that a lender will not be subject to disparate impact liability based on specific actions undertaken to avoid liability under the Dodd-Frank rules, such as making only or primarily QM safe harbor loans or limiting QM rebuttable presumption or non-QM loans to borrowers whose risks of default are low.”
To read the full letter, click here.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →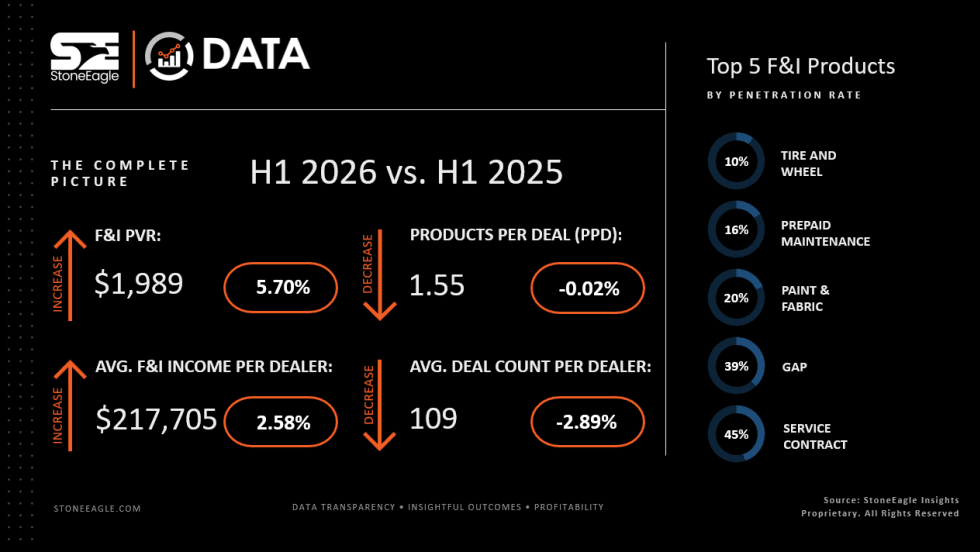
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →