



Wells Fargo Realizes Record Earnings in Q3
The bank was active in the third quarter, increasing its core loan portfolio by $11.9 billion. Officials attributed the bank's record performance to improving credit quality.
SAN FRANCISCO —Wells Fargo realized record earnings in the third quarter behind an $11.9 billion increase in its core loan portfolio — which includes mortgage, auto, credit card, as well as commercial and student lending — from the previous quarter. Officials said they expect to expand that even more in coming quarters.
The bank reported total revenue of $21.2 billion, up 8 percent, while net income was up 27 percent from the prior quarter to a record $4.9 billion. For the first nine months, net income was up from $11.8 billion a year ago to $13.8 billion
Wells also reported total loans of $782.6 billion, up $7.4 billion from the prior quarter. Officials said the increase was fueled mainly by improved credit quality, which allowed Wells Fargo to reduce its allowances for credit losses from $18.8 billion in the previous quarter to $17.8 billion.
“Underlying credit quality continued to show improvement in the third quarter, as the overall financial condition of businesses and consumers strengthen, the housing market in many areas of the nation improved, and we continue to work to reduce problem assets and make new, high quality loans,” said Chief Risk Office Mike Louglin.
The bank’s mortgage business lead the way, with new mortgage loan originations rising from $89 billion a year ago to $139 billion. Auto originations totaled $6.3 billion in the quarter, which was down 3 percent from the prior quarter but up 20 percent from the year-ago period.
Net loan charge-offs during the quarter were $2.4 billion, which included $567 million in net charge-offs due to the implementation of newly rules issued by the Office of the Comptroller of the Currency (OCC). The bank also reported that loans 90 days or more past due totaled $1.5 billion, up from $1.4 billion in the prior quarter.
“Excluding the impact of the OCC guidance, we saw improvement in charge-offs, recoveries and nonperforming assets,” said Louglin, noting that the bank released $200 million it had set aside earlier to cover possible loan losses. “Early stage delinquencies remained relatively stable from the prior quarter. Absent significant deterioration in the economy, we continue to expect future reserve releases.”
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →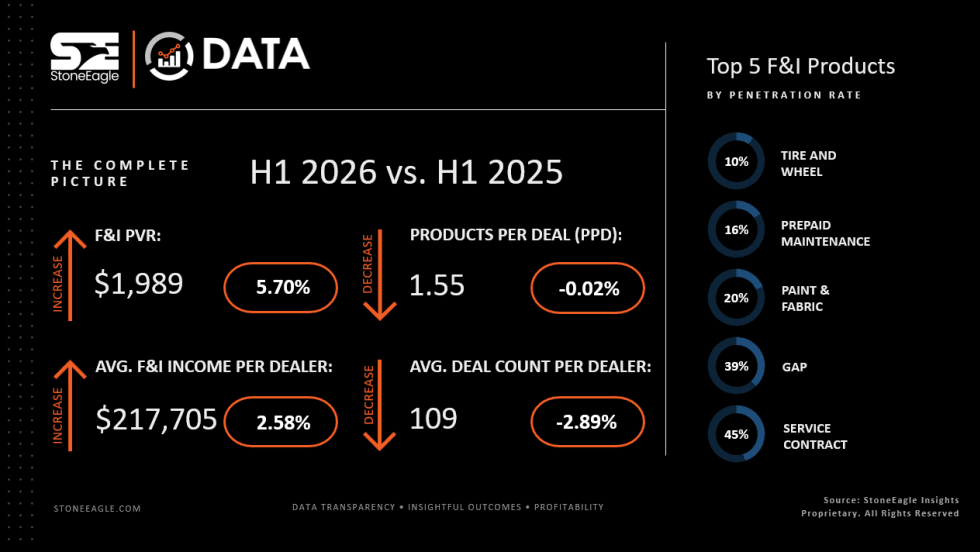
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →