

A Robust Future for Used-Car Sales and CUs
Credit unions have gained market share as other finance sources have retrenched, creating new incentive to diversify your selection finance sources.
Credit unions funded 19.2% of all U.S. auto loans in 2017, registering an industry-leading 13.5% one-year market-share gain. Photo courtesy Architectural Polymers via Flickr
Consumer interest in quality used cars — including older, higher-mileage models — will continue strong through 2018. In addition, the increase of off-lease vehicles will give buyers more choices across more price points than the industry has seen in some time.
This increased off-lease volume may bring with it declining used car values, which means dealers will look to:
• Laser-focus on vehicle acquisition cost and quality.
• Increase sales margins by reconditioning cars faster, so they get to the sold line quicker.
• Competitive price to market to gain buyer attention.
• Leverage credit unions with a long history of helping dealers increase used auto sales.
Credit unions have become a very valuable partner for dealers, providing excellent locations to go to get paper bought, and an additional channel of comparative lending.
A dealer working with local credit unions has a true advantage — a flexible finance option that will help drive used cars sales. Dealers like using credit unions for both new- and used-car purchases, because credit unions understand their members and consumer loan flexibility, as well as having better rates than most other lenders.
Marketplace Strength
Consistently, 70% of credit union auto loan portfolios are used cars, reflecting the used-car finance market strength of these lenders. The credit union member is a good prospect. With more than 5,600 credit unions nationwide, representing more than 110 million credit union members, one in three Americans — and half of all employed Americans, are credit union members. This is a dynamic market segment increasingly pursued by auto dealers, which is why auto loan originations by the nation’s credit unions are setting a record pace.
Recent auto loan data continue to confirm the robust position credit unions enjoy. Credit unions held 19.2% of the vehicle finance market share, according to Callahan & Associates, and as a whole experienced almost 12% loan growth through year-end 2017, leading all lender types.
Dealers engaging credit union members recognize these buyers’ affinity to their local communities — and their credit union’s endorsement of local businesses, including auto dealers.
It’s partly because of this synergy that auto dealers who work with credit unions to originate auto loans enjoy significant market advantages. These lenders provide greater loan flexibility for consumers to buy more vehicle than they might otherwise. These consumers typically purchase one or more aftermarket products, such as a vehicle service contract, GAP, or prepaid maintenance to protect their vehicle investment and budget.
CU Direct’s 1,100 credit unions became the nation’s leading auto lender in 2017, with 16.2% loan growth year-end, the second-highest loan-origination growth rate among the top 10 lenders in the country, according to data from AutoCount. Through February of 2018, we’ve seen this trend continue, as credit unions on the CUDL platform have maintained their No. 1 position in the marketplace, experiencing 13.5% year-over-year growth.
Credit unions on my company’s platform funded 1.8 million loans last year, generating a record $39 billion in credit union auto loans, surpassing the company’s record $32 billion in loans funded in 2016. There is recognized value in using lending technology that opens the door for dealers to work with and expedite loans through credit unions, for which market growth has come, in part, from the market pullback by some banks and other finance sources.
What This Means for Dealers
Auto lending is one of the cores of what credit unions do, and they continue to be aggressive in expanding their auto portfolios because their collective relationship with dealerships is as good as it’s ever been.
As a result, credit unions are seizing the opportunity in auto lending, and we don’t anticipate that tapering off. When it comes to retail auto lending, credit unions are the only finance sector that has exhibited growth and grown portfolios.
For dealers to effectively tap into the growing consumer interest in purchasing used cars to increase sales, gain new customers, and build brand loyalty, collaborating with credit unions makes good business sense.
Bob Child is the COO at CU Direct and a 25-year industry veteran. Contact him at bob.child@bobit.com or (877) 744-2835.
More F&I
Modern Technology Objection Handling
In this video, Trent White shares how to confidently handle technology-based objections by helping customers understand the value of protection, even with modern vehicle technology.
Read More →
Consistency at Scale: Driving F&I Performance
With 75 rooftops across the Sunshine State, Morgan Auto Group has proven to Floridians that it knows a thing or two about driving performance in a competitive market. But it didn’t start at the top.
Read More →
Gitty Up on GAP
The foundational finance-and-insurance product hasn’t kept up with the latest conditions for auto dealers. Is the time ripe?
Read More →
How AI-Powered Coaching Is Transforming F&I Performance
See how AI-powered coaching can turn F&I customer conversations into actionable insights that support compliance, performance and profitability
Read More →
Sell Value, Build Trust
In this video, Trent White explains why selling on value, not fear, builds lasting customer trust, reduces cancellations, and drives long-term success.
Read More →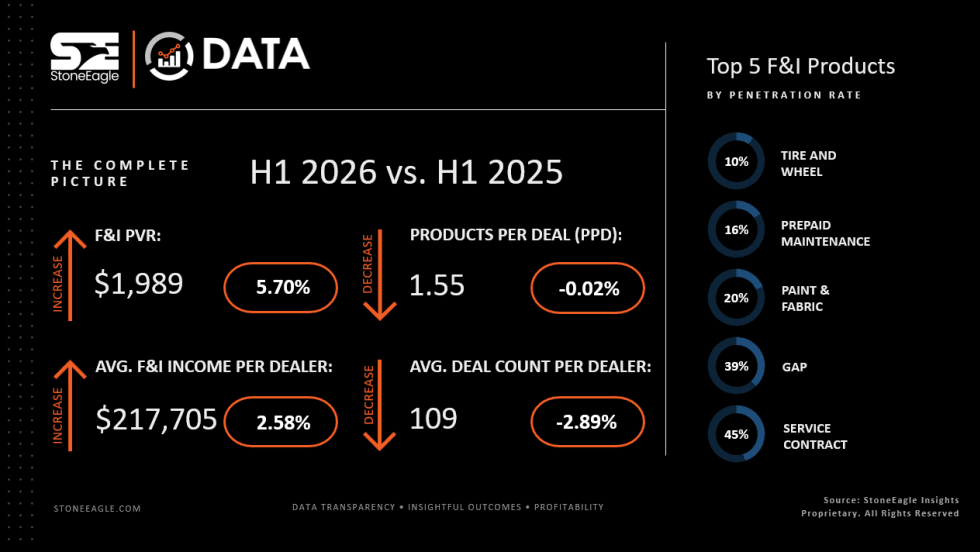
F&I Sales Give Dealers First-Half Lift
Product business shored up total profits to avoid an overall revenue tanking as product penetrations held steady, StoneEagle reported.
Read More →
Targeted Training Drives Results
Today’s technology, instead of threatening F&I managers, can actually make them better, according to an industry veteran who’s watched market setbacks roil the unprepared.
Read More →
Double the Change, Double the Chance
When an F&I manager gets a customer refusal, it’s a wise move to tweak more than one thing in the product offering.
Read More →
Just Do It
F&I managers need training, but instead of resisting application or expecting perfection, they should improve by simply acting on what they learn.
Read More →
Dealer Lender Preferences Revealed
When lenders provide consistent, fast service, their overall satisfaction scores with dealers greatly improve, according to JD Power research.
Read More →